
A couple in Chelmsford recently asked a question I hear often: “Are we too old for a normal mortgage, and does equity release mean the debt just keeps growing?” The short answer is no, and not always.
💡 Top tip: many people assume later life borrowing means giving up control or watching the balance spiral, but that isn’t the whole picture. In some cases, paying some or all of the interest can keep things far more manageable, and I’ll explain exactly how that works later in the article.
Introduction
If you’re looking at mortgages over 55, you’re not alone. For many homeowners across Essex, including Colchester and Braintree, the family home has become their biggest asset, but their monthly income may be changing as retirement gets closer.
That creates a very specific kind of crossroads. You may still have a mortgage to clear. You may want to remortgage for a better deal. You may need funds for home improvements, to repay existing borrowing, or to make retirement feel more comfortable. The difficulty is that borrowing in your late 50s, 60s or beyond doesn’t work exactly like it did earlier in life.
The pressure is real. In the UK, one in five (20%) mortgaged homeowners over 55 do not expect to retire mortgage-free, and 31% of UK consumers now see property wealth as a way to improve retirement finances, according to the Equity Release Council’s later life lending research.
That doesn’t mean one product suits everyone. It means your options need to match your stage of life.
Practical rule: the right later life mortgage usually comes down to one question first. Can you show enough reliable income to support monthly payments, or do you need a solution with more flexibility?
Some people over 55 still fit a standard remortgage. Others are better suited to a Retirement Interest-Only mortgage, often called a RIO. There will be others who need the flexibility of a Lifetime Mortgage, the most common type of equity release. Each route works differently, and each has trade-offs around affordability, access to cash, and what may be left for your family later on.
Understanding Your Mortgage Options Over 55
For most homeowners, there are three broad routes to consider. The easiest way to understand them is to think about what the lender expects from you each month.
Standard mortgages and remortgages
A standard mortgage is the familiar option. You borrow money and make monthly repayments that usually cover both capital and interest.
This can still work after 55, especially if you’re still employed or have high self-employed income and a sensible term. The challenge is that many lenders won’t want the mortgage running too far into later retirement unless they’re comfortable that the payments will still be affordable then.
A shorter term can help you clear the mortgage sooner, but it also means higher monthly repayments. That’s often the sticking point for borrowers in their late 50s and early 60s.
Some lenders will allow for Interest-Only mortgages up to retirement, assuming the method of repaying the mortgage is either the sale of the mortgaged property, or there are other assets to use in the background, such as a pension, investment, or other property.
RIO mortgages
A Retirement Interest-Only mortgage sits between a standard mortgage and equity release. You make the interest payment each month, but you don’t repay the original capital balance during the term. The capital is usually repaid when the property is sold, commonly after death or a move into long-term care.
That can reduce the monthly burden compared with a full repayment mortgage. It’s often attractive to homeowners who want to keep monthly costs lower while protecting more of their property value for inheritance.
If you want a more detailed look at how this works in practice, this guide to a Retirement Interest-Only mortgage is a useful next read.
Lifetime mortgages
A Lifetime Mortgage is the most popular form of equity release. It lets you borrow against your home without mandatory monthly repayments, and the loan is usually repaid from the eventual sale of the property. The amount available depends partly on age, with maximum Loan-to-Value ratios starting around 20 to 30% at age 55 and rising to 58% for older applicants, based on the Lifetime Mortgage overview referenced here.
People often get nervous. They hear “rolled-up interest” and assume the product is automatically unsuitable. That isn’t right. Many plans allow borrowers to service some or all of the interest, which can reduce or even stop the balance increasing in the way many fear.
A later life mortgage isn’t simply about age. It’s about matching the product to the way your income works now, and how you want your finances to work later.
A simple way to think about it
Standard mortgage means you repay capital and interest
RIO means you pay interest only
Lifetime Mortgage means there may be no required monthly payment
If your concern is wider household pressure, it can also help to understand related support options. This article on understanding Support for Mortgage Interest gives useful background in plain English.
Qualifying for a Later Life Mortgage
A lot of Essex homeowners reach the same crossroads around their mid-50s and beyond. They can afford something, but they are not always sure what they can afford for the long run. That is the point lenders focus on too.

The key test is usually simpler than people expect. A lender wants to know where your income comes from now, whether it is likely to continue, and how the mortgage will be repaid later.
Age still matters, of course. Some lenders have maximum ages at application or at the end of the term. But age on its own rarely answers the question. Two homeowners in Chelmsford who are both 62 can get completely different results if one has strong pension income and the other is relying on savings that are being used up each month.
If you’re still working
If you are employed or self-employed, a lender will usually start with the same basic checks used on other residential mortgages. They will look at earnings, regular commitments, credit history, and how long the mortgage is meant to run.
For borrowers in their late 50s, the retirement date becomes more important. Lenders are asking a practical question. Will the mortgage still be affordable once work slows down or stops?
A simple way to picture it is this. Your current income opens the door, but your retirement income often keeps it open.
Evidence often includes:
Payslips and P60s for employed applicants
SA302s, tax year overviews, and accounts for self-employed applicants
Pension statements if retirement income will support the case later. A projection on any Pension income at retirement is key.
Bank statements or proof of assets where a lender accepts savings or investments as part of the wider picture
If those documents show a clear path from earned income to retirement income, a standard remortgage or a RIO may both stay on the table.
If you’re retired or nearly there
Once retirement is close, lenders pay far more attention to income that is expected to continue. That often means state pension, workplace or private pensions, drawdown income, annuities, rental income, or certain investment income.
This is often the point where the choice between a RIO and equity release becomes clearer.
A RIO mortgage works a bit like keeping a kettle on a low simmer. You are still making monthly interest payments, so the loan balance itself does not grow just because interest is being added on. That can matter a great deal if leaving money to children or grandchildren is high on your list.
A lifetime mortgage works differently. Many plans do not require monthly payments, which can ease pressure on day-to-day budgeting, but interest may be added to the loan over time. For some households, that flexibility is the right answer. For others, the trade-off on inheritance feels too great. With more Lifetime Mortgages allowing for some or all of the interets being payed each month, the lines between RIO and Lifetime Mortgages is more blurred.
So the actual question is not just, “Am I too old?” It is usually, “Can I comfortably maintain monthly payments from reliable retirement income, or do I need a product that removes that pressure?”
What lenders are really assessing
Lenders usually look at later life applications through four main lenses:
| What they check | Why it matters |
|---|---|
| Reliable income | They need to see how monthly payments will be covered now and in retirement, if payments are required |
| Credit history | Missed payments, heavy unsecured debt, or recent adverse credit can reduce the number of lenders willing to help |
| Property suitability | The home is the security, so value, construction type, and condition all affect what is available |
| Exit plan | For term lending, lenders want to know how the mortgage ends. For later life products, they assess whether the structure fits your age and circumstances |
That last point causes a lot of confusion. A standard mortgage has a fixed term and a clear repayment route. A RIO usually continues until death or a move into long-term care, with interest paid monthly throughout. A lifetime mortgage is also repaid later, usually from the sale of the home, but it does not rely on the same monthly affordability model.
That is why affordability and age sit at the centre of the decision. If your pension income can comfortably support monthly interest, a RIO may help protect more of your equity. If monthly payments would feel tight or uncertain, equity release may be more realistic, even if preserving inheritance matters to you.
There is no single right answer for every homeowner in Essex. The best fit depends on what you can prove on paper, what you can manage in real life, and how strongly you want to protect the value left in your home.
Here’s a useful video that gives more context around later life borrowing and the kinds of issues lenders consider:
Key point: borrowers who can show steady income for monthly payments usually have more later life mortgage options. Borrowers who cannot may still have choices, but the balance often shifts towards flexibility rather than inheritance protection.
A Head-to-Head Comparison of Your Choices
The best product usually becomes clearer when you compare what each one asks you to do, and what each one gives you in return.
A homeowner in Braintree might want to keep monthly costs as low as possible because retirement is close. Someone in Colchester may still have strong earned income and want a better remortgage deal. Another borrower may care most about leaving as much equity as possible to children or grandchildren. Those priorities point in different directions.
Mortgage options over 55 compared
| Feature | Standard Remortgage | RIO Mortgage | Lifetime Mortgage |
|---|---|---|---|
| Monthly payments | Capital and interest are repaid monthly | Interest is paid monthly | No mandatory monthly payments on many plans |
| Capital repaid | During the mortgage term | Usually when the property is sold | Usually when the property is sold |
| Affordability focus | Strong focus on income and term | Strong focus on pension or investment income for interest payments | Less dependent on monthly affordability in the same way |
| Inheritance impact | Often lowest impact if repaid as planned | Can preserve more equity if interest is maintained | Can reduce inheritance more if interest rolls up |
| Best suited to | Borrowers with solid ongoing income | Borrowers who can afford monthly interest but want lower payments | Borrowers needing flexibility or unable to support monthly payments |
Where each option tends to work best
A standard remortgage is often best when you still have enough income to support a normal term and want to pay the debt down in a familiar way. It’s the least specialist route, but it isn’t always available for older borrowers because age and retirement planning can limit term length.
A RIO mortgage suits borrowers who can show reliable pension or investment income and want to keep the balance level by covering the interest each month. It’s often a strong middle ground.
A Lifetime Mortgage is usually the most flexible if affordability is the obstacle. It can work well for people who are asset-rich but income-light. If you want a broader look at that route, this guide to equity release over 55 explains the basics clearly.
The inheritance concern
This is the emotional part of the decision, and rightly so. Many clients worry less about the borrowing itself and more about what will be left behind.
That concern is sensible, but it shouldn’t lead to assumptions. A RIO often protects more equity because you keep paying the interest. A Lifetime Mortgage may reduce inheritance more if interest is allowed to roll up for many years. But modern later life lending is far more flexible than many people think, and some plans include inheritance protection features.
Borrowers usually feel more confident once they stop asking “What’s the cheapest product?” and start asking “Which product fits the way I want to live and leave things?”
A note on flexibility
Each lender has its own rules on overpayments, moving home, and early repayment. That’s one reason later life advice matters so much. What looks similar on the surface can behave very differently once you get into the detail.

A Real-World Example and Common Myths Debunked
One recent client was close to retirement, had a small outstanding mortgage of around £50,000, a credit card balance of £8,000, and wanted to replace their kitchen at a cost of over £20,000. Their future income was likely to be tighter once they stopped working, so a normal mortgage route was unlikely to be the best fit.
A Lifetime Mortgage provided £80,000 on a home worth £320,000. Significantly, the client chose to service the interest in full each month, which meant the mortgage balance would not increase over time in the way many people fear.
That example matters because it shows how later life lending is often about solving several problems at once. It cleared existing debt, funded improvements to the home, and created a structure that still felt controlled and understandable.

“Many people think equity release means handing over your deeds and leaving nothing for the family. In reality, all Lifetime Mortgages can include inheritance protection, and paying some or all of the interest can help stop the debt growing over time.”
Myth 1 : you lose your home
That’s one of the most common misunderstandings. With a Lifetime Mortgage, you still retain ownership of your home. The lender has a charge against it, as with other traditional mortgages, but it does not mean you stop owning the property.
Myth 2 : nothing will be left for the family
That depends on the product chosen and how it is managed. If interest rolls up for many years, the balance can grow significantly. But that isn’t the only way these plans can work. Some borrowers make interest payments, and some choose products with inheritance features.
Myth 3 : equity release is only for people in difficulty
Not at all. People use later life lending for debt consolidation, home improvements, helping family, or making retirement finances more practical. The key issue isn’t whether the reason sounds dramatic. It’s whether the solution is suitable and fully understood. What may have seemed somewhat ‘taboo’ a few years ago is becoming more popular and used for a multitude of reasons, including early inheritance and estate planning.
The Application Process with a Broker
A later life mortgage application feels much easier when you know the order of events. Most cases follow a clear path.
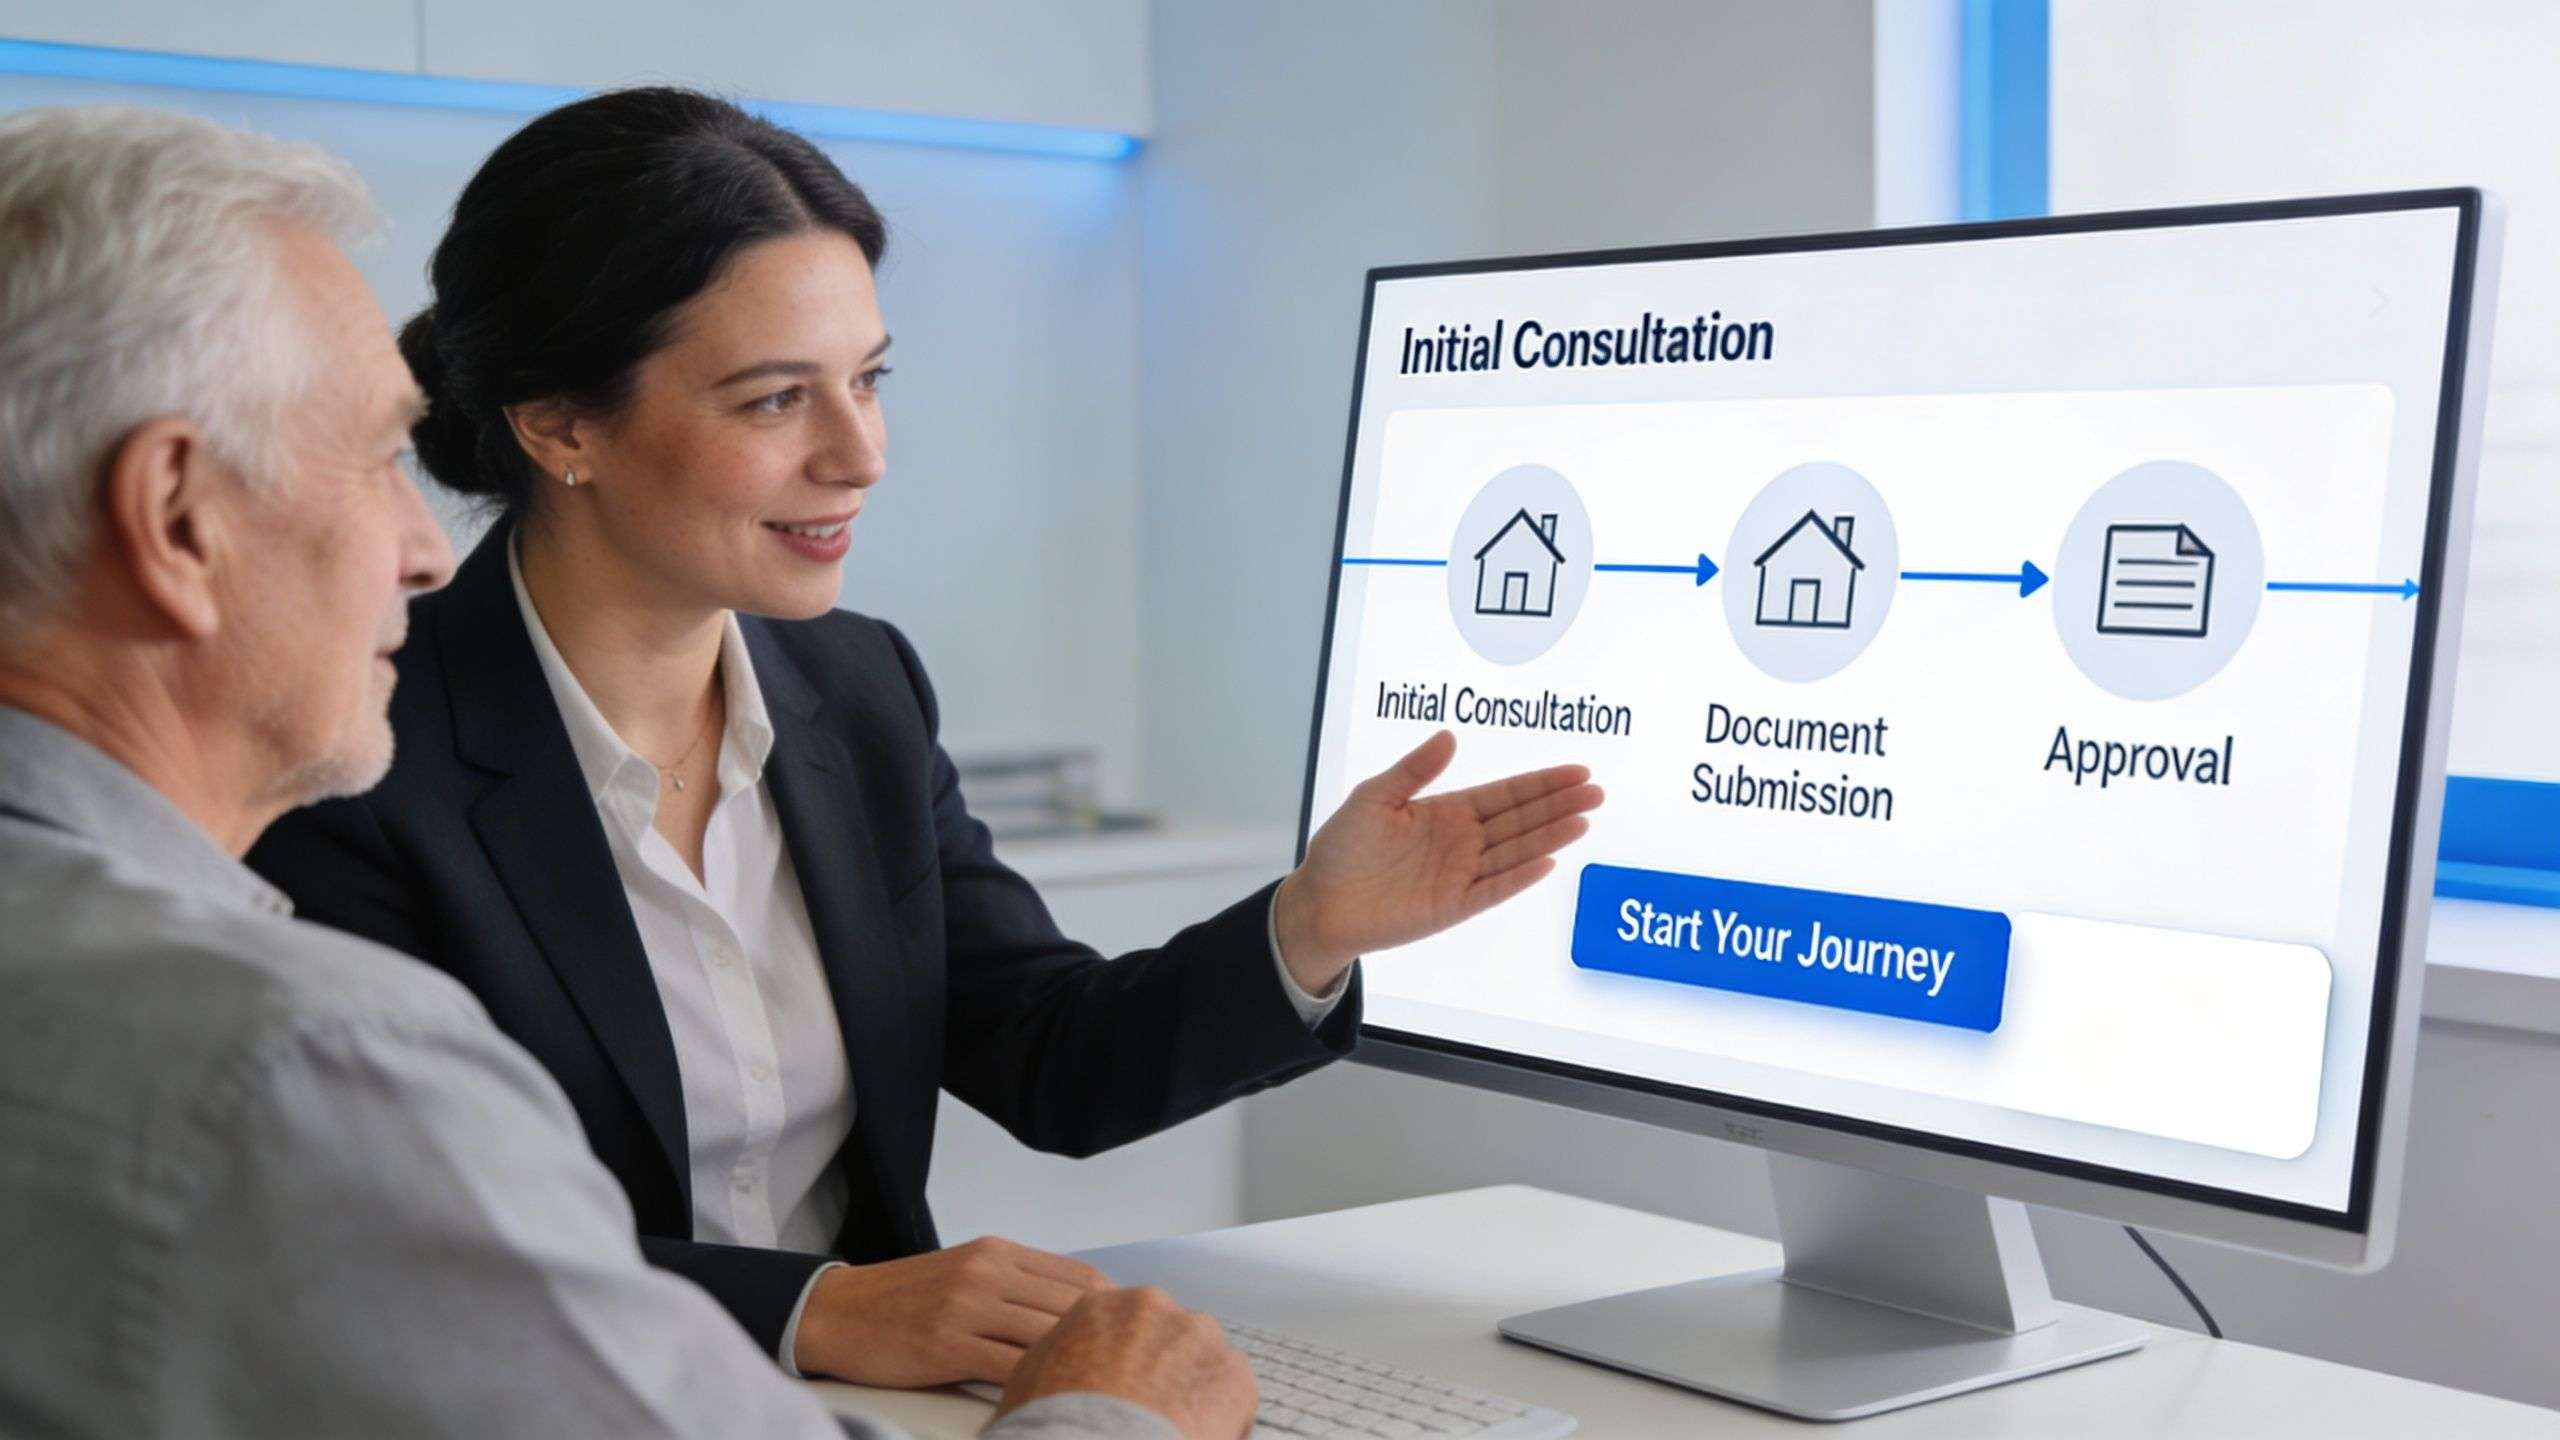
Step 1 : Initial Fact-Find
Your income, existing mortgage, property value, age, plans for retirement, and family priorities are discussed in detail. For later life lending, the conversation needs to be thorough because the best answer depends on more than rate alone.
Step 2 : Recommendation
Once the facts are clear, the adviser narrows the market and recommends the most suitable route. That may be a standard remortgage, a RIO, or a Lifetime Mortgage.
If you’re choosing who to work with, this guide on how to choose a mortgage broker is worth reading.
Step 3 : Initial Agreement and Application
For products that use affordability in the usual way, the adviser will gather income evidence and approach suitable lenders. For equity release, the focus may sit more heavily on age, property, and product features.
At this stage, paperwork matters. Clear pension documents, mortgage statements, ID, and proof of address help avoid delays.
Step 4 : Valuation and Offer
The lender will assess the property and review the case. If everything fits, a formal offer follows. If the lender has questions, the adviser deals with them and keeps the case moving.
The best broker work often happens behind the scenes. Chasing paperwork, matching lender criteria properly, and spotting issues early saves a lot of stress.
Step 5 : Legal Work and Completion
A solicitor handles the legal side, explains the documents, and completes the transaction. Once funds are released, the old mortgage may be repaid, the new borrowing starts, and any additional money is available for your agreed purpose.
Key Questions Answered About Mortgages Over 55
The questions that keep people awake at night are rarely about the headline rate. In Essex, the sticking point is often this: can I afford monthly payments in retirement, or do I need a plan that removes that pressure, and what does that mean for my family later?
That is the crossroads between a RIO and Equity Release.
Will a later life mortgage affect my benefits?
It might. The key issue is usually not the mortgage itself, but what happens to any money you release.
If funds are paid into your bank account and sit there, that can affect means-tested benefits because your savings position has changed. If you are receiving benefits now, or may need to claim later, this needs checking before you apply, not after completion.
Can I move house later?
Often, yes. But you should never assume every product will move with you.
Many later life mortgages are portable, which means you may be able to take the mortgage to a new property if the lender agrees and the new home fits their rules. That matters in real life. A bungalow in Clacton, a flat in Chelmsford, and a cottage in a village outside Braintree will not always be treated the same way by a lender.
If downsizing is part of your long-term plan, ask about this at the start.
What happens to inheritance?
This is usually the biggest worry, and it is a sensible one.
A RIO works more like keeping the roof patched up as you go. You pay the interest each month, so the balance itself does not usually grow just because time passes. That can leave more of the property value intact for your estate, provided the payments stay affordable.
With equity release, interest may roll up over time if you choose not to make payments. That can reduce the amount left from the sale of the property later. It does not automatically mean there will be nothing to leave behind, but it does mean inheritance needs to be part of the decision, not an afterthought.
Is Equity Release better than a RIO?
The better option depends on one question first. Can you comfortably afford the monthly interest from retirement income, both now and later?
If the answer is yes, a RIO may suit someone who wants to keep control of the balance and protect more equity for their children or other beneficiaries. If the answer is no, equity release may be more suitable because it removes the need to pass an affordability test in the same way and can ease pressure on monthly budgeting.
A simple way to sort your thinking is:
Choose a RIO if your pension or investment income can clearly support the monthly interest and preserving equity matters to you
Consider equity release if regular payments would feel strained or uncertain in retirement
Use a standard remortgage if you still meet normal affordability rules and want the broadest product choice
For many homeowners over 55, age is not the main barrier. Affordability is. Once you understand that, the choice becomes much clearer.
Your Next Steps with EHF Mortgages
Mortgages over 55 aren’t just about borrowing later in life. They’re about choosing the right balance between monthly affordability, flexibility, and inheritance.
For some homeowners in Chelmsford, a standard remortgage still does the job. For others in Braintree or Colchester, the decision lies between a RIO and a Lifetime Mortgage. The difference often comes down to whether pension or investment income is strong enough to support monthly interest payments.
That’s where good advice earns its place. The details matter. Product features matter. The way your retirement income is presented matters. Most of all, your plans for the future matter.
If you want clear, individualized guidance from an Essex broker that understands later life lending, the next step is simple. Have a proper conversation about your circumstances, your income, and what you want this mortgage to achieve.
If you’re ready to discuss your options with EHF Mortgages, get in touch through the contact page below.





