
Gifted Deposit Mortgage: Your Complete Guide
Ready to get on the property ladder but worried about the deposit?
💡 Top Tip: Always get a signed letter from the person gifting you money, stating it is a true, no-strings-attached gift.
We’ll explain exactly why this is non-negotiable later in the article.
Table of Contents
For many aspiring homeowners, saving up a big enough deposit feels like the biggest hurdle, especially for first-time buyers in competitive areas like Essex. A gifted deposit mortgage, where a family member helps you out with the funds, is a popular and powerful way to get you onto the property ladder much sooner than you might think.
Think of it as a launchpad for your homeownership journey, giving you the boost needed to secure your dream home.
The Growing Importance of Family Support
In the UK mortgage market for 2025-2026, gifted deposits have become a vital lifeline for first-time buyers trying to keep up with house prices. This is especially true in high-value areas across Essex. Family assistance is now a common part of the home-buying process, and lenders are increasingly open to this type of deposit funding.
With the average first-time buyer age now at 34, it is no surprise that many younger buyers in places like Chelmsford and Braintree are turning to parents or grandparents for a helping hand.
This guide will walk you through everything you need to know about securing a mortgage with a gifted deposit. We will cover the basics, the paperwork, and the legal details to make the whole process clear and straightforward.
“A gifted deposit mortgage is not just about receiving money; it is about correctly documenting a generous act to satisfy lender requirements and unlock the door to your new home. Clarity and preparation are your best assets.”
We understand the specific challenges of buying a property in bustling Essex towns like Colchester, and this guide is your roadmap to success. A key first step is preparing your finances. To give your savings an extra boost, it is worth exploring options like the Lifetime ISA UK, which offers a significant government bonus for first-time buyers.
By understanding how a gifted deposit works, you can confidently take this significant step toward owning a home and turn family support into a tangible reality.
What a Gifted Deposit Is and How It Works
So, what exactly is a gifted deposit? Think of it as a generous head start in the race to buy your own home, kindly provided by a loved one. It is a sum of money given to you to cover some or all of your property deposit.
But here is the crucial point for any mortgage lender: the money has to be a genuine gift, not a sneaky loan in disguise. This means there can be absolutely no expectation of repayment, and the person giving you the money will not have any legal claim over your new property.
The Mechanics of a Gifted Deposit Mortgage
In practice, using a gifted deposit is usually quite straightforward. A family member – most often a parent or grandparent – provides you with the funds. You then add this money to your own savings to create a much healthier deposit for your property purchase.
Let us look at a real-world example. Imagine you are buying a £300,000 home in Colchester. You have diligently saved £15,000, but a family member gifts you another £15,000. Your total deposit is now £30,000.
Just like that, you have gone from having a 5% deposit to a 10% one. This is incredibly powerful. It brings down your Loan-to-Value (LTV) ratio – the percentage of the property’s price you need to borrow. A lower LTV makes you a far more attractive, lower-risk applicant in the eyes of lenders. This often unlocks better mortgage rates and more favourable terms, saving you a significant amount of money over the life of your loan.
“A gifted deposit is more than just cash; it is a key that unlocks better mortgage deals. By lowering your Loan-to-Value ratio, it signals to lenders that you are a lower-risk borrower, which often translates directly into lower monthly payments.”
Who Can Provide a Gifted Deposit?
Lenders have clear guidelines on who they will accept a gift from. Their main priority is to prevent financial crime and make sure the money is legitimately yours, with no strings attached.
Immediate Family: Lenders are most comfortable with gifts from parents, grandparents, and sometimes siblings. The relationship is easy to prove, and the “gift” nature of the transaction is more believable.
Extended Family and Friends: Some lenders will consider gifts from aunts, uncles, or even very close friends. Be prepared for more scrutiny here, as they will want to be certain it is not a loan.
Other Sources: In rare cases, a vendor or property developer might contribute your deposit. These are less common and will be examined with a fine-tooth comb.
Because the rules are so strict, it is vital to be upfront with your mortgage broker and solicitor from day one. Declaring the gift early prevents frustrating delays down the line and allows all necessary anti-money-laundering checks to be completed smoothly. For a full checklist of what you will need, you can learn more about what is required for a mortgage deposit in our detailed guide.
Key Steps in the Gifted Deposit Process
The journey from receiving the gift to getting your keys involves a few simple but non-negotiable steps. Being prepared makes all the difference.
Receive the Funds: Your family member transfers funds to your bank account.
Inform Your Broker: Tell your mortgage adviser straight away that part of your deposit is a gift.
Prepare the Gift Letter: The person gifting the money (the “donor”) must sign a formal letter confirming the gift’s details.
Provide Documentation: Both you and the donor will need to provide ID and bank statements to prove the source of the money.
Solicitor Verification: Your solicitor will verify all these documents to satisfy legal requirements and keep the lender happy.
Navigating these steps with an expert adviser ensures no detail is missed, paving the way for a successful gifted deposit mortgage application.
Understanding Lender Criteria for Gifted Deposits
While most UK lenders are happy to accept a gifted deposit, they have to follow strict rules. Their main goal is simple: to make certain the money is a genuine gift and not a loan in disguise. This protects them from risk, but it also protects you from any messy complications down the line.
Being completely transparent about your gift from the very beginning is the surest way to a smooth mortgage application. Lenders need to be confident that no repayment is expected and there are no hidden strings attached. They also have a legal duty to comply with UK anti-money laundering regulations, which means they must verify the source of every penny used to buy a property.
Who Lenders Prefer the Gift to Come From
Lender confidence often comes down to your relationship with the person giving you the money, known as the donor. A close family connection is almost always the easiest route, as the “gift” nature of the money is much clearer.
Close Family Members: Gifts from parents, grandparents, and sometimes siblings are universally accepted. The relationship is easy to prove, making the whole process very straightforward.
Wider Family and Friends: Some lenders will consider gifts from other relatives, such as aunts, uncles, or very close friends. If this is your situation, expect a few more questions to confirm it is a true gift with no expectation of repayment.
Other Sources: In much rarer cases, a contribution might come from a builder or the property seller. These are scrutinised heavily, and many lenders will not accept them at all.
Our whole-of-market expertise means we know exactly which lenders are more flexible. We can match you with a provider whose criteria fit your specific circumstances, whether you are buying in Chelmsford or anywhere else in Essex.
“Being upfront and honest with your lender about the source of your deposit is non-negotiable. Full transparency from day one is the fastest route to a successful mortgage offer.”
How a Gifted Deposit Strengthens Your Application
A gifted deposit can do wonders for your mortgage application, especially for buyers in competitive markets. For someone looking to buy in Essex, for instance, a larger deposit can push you into a lower Loan-to-Value (LTV) bracket. This makes you a less risky borrower in the lender’s eyes and often unlocks much better interest rates.
To get a better handle on this, check out our guide to the loan-to-value ratio and its importance.
Gifted deposits are playing a huge role in helping people get onto the property ladder. In fact, various government-backed schemes have helped an extra 46,000 first-time buyers, in part because gifted funds count fully towards the required deposit.
Let us see how this works in practice.
Impact of a Gifted Deposit on a £400,000 Property Purchase
This table shows how different gift amounts can dramatically improve your position when buying a typical Essex home.
| Total Deposit | Gifted Amount | Mortgage Required | LTV | Potential Benefit |
|---|---|---|---|---|
| £20,000 (5%) | £10,000 | £380,000 | 95% | Access to 95% LTV mortgages |
| £40,000 (10%) | £20,000 | £360,000 | 90% | Unlocks better interest rates |
| £60,000 (15%) | £30,000 | £340,000 | 85% | More lenders & better rates |
| £80,000 (20%) | £40,000 | £320,000 | 80% | Significant rate discounts |
As you can see, a generous gift does not just help you reach the deposit finish line, it actively lowers your LTV, which can save you a substantial amount of money over the life of your mortgage.
Common Lender Conditions and Checks
Beyond knowing where the gift came from, lenders have a standard checklist of conditions. This is normal practice and ensures the transaction is secure and fully compliant.
Here are the most common requirements you will face when applying for a gifted deposit mortgage:
A Signed Gift Letter: This is a mandatory document. The donor must sign a formal letter stating the amount, confirming it is an unconditional, non-repayable gift, and declaring they will have no legal interest or stake in the property. The lender may also provide this as a template for their own process, so let your Mortgage Broker advise you on this requirement.
Proof of Identity: Lenders will need to see a valid photo ID for the person (or people) gifting the money. A passport or driving licence is usually required.
Proof of Funds: This is the most detailed part of the check. The donor will need to provide bank statements showing the origin of the money. Lenders need a clear audit trail to satisfy the all-important anti-money-laundering regulations. Clearly demonstrating where the funds have come from may require several statements and documents, so please be prepared for this.
By getting these documents ready ahead of time, you can prevent any last-minute hold-ups and keep your mortgage application moving forward smoothly.
Essential Paperwork for Your Gifted Deposit
Getting the paperwork right is one of the most important steps when using a gifted deposit. Lenders have very strict rules to prevent financial crime, so providing clear, accurate documentation from the start is crucial. Mess it up, and you could face frustrating and costly delays.
Think of it as creating a transparent story for the lender, showing them exactly where the money has come from. A simple mistake – like a poorly worded letter or a missing bank statement – could put your entire property purchase in Braintree at risk. This is where an experienced mortgage broker becomes invaluable, checking every document before it even lands on a lender’s desk.
Your solicitor also plays a key role, as they will independently verify the paperwork to ensure the transaction is legally sound and watertight.
While UK mortgage commitments dipped in early 2026, the market has been propped up by the continued use of gifted deposits. Lenders have adapted their underwriting but now demand rigorous proof to stamp out ‘borrowed gifts’. This means donor bank statements and correctly drafted gift letters are non-negotiable. You can read further analysis on shifting lender views to understand how the landscape is changing.
Your Gifted Deposit Document Checklist
To keep things organised, here is a clear checklist of the essential documents both you and the person gifting the money (the donor) will need to provide. Preparing these items in advance will significantly speed up the process.
| Document | Provided By | Purpose | Key Details to Include |
|---|---|---|---|
| Gifted Deposit Letter | The Donor | To formally declare that the funds are a true gift | Names, relationship, gift amount, ‘no repayment’ clause |
| Proof of Identity | The Donor | To verify the donor’s identity (AML checks) | Valid passport or driving licence |
| Proof of Address | The Donor | To confirm the donor’s current residence | Recent utility bill or council tax statement |
| Source of Funds | The Donor | To trace the origin of the money (AML checks) | Bank statements showing the funds and their source |
| Buyer’s Bank Statements | The Buyer | To show the gifted funds arriving in your account | Statements showing the deposit transfer from the donor |
This list forms the backbone of your gifted deposit evidence. Your mortgage adviser and solicitor will guide you on the specific requirements of your chosen lender, ensuring every piece of the puzzle fits perfectly.
The Gifted Deposit Letter: The Most Important Document
Of all the paperwork, the gifted deposit letter is the one you absolutely cannot get wrong. This is a formal, signed declaration from the donor confirming the money is a genuine gift with no strings attached.
A lender will reject any letter that even hints that the money might be a loan. It is a deal-breaker. The letter must explicitly state:
The donor’s full name and address.
Your full name (the recipient).
The exact amount of the gift.
A clear statement that the money is an unconditional and non-repayable gift.
A declaration that the donor will hold no legal charge or interest in the property being purchased.
“The gifted deposit letter is the cornerstone of your application’s credibility. It must be unambiguous, leaving no doubt in the lender’s mind that the funds are a true gift, free from any expectation of repayment or stake in the property.”
Verifying the Source of Funds
Proving where the money came from is not about the lender being nosy; it is a legal requirement to comply with Anti-Money Laundering (AML) regulations. Every penny must be accounted for to ensure it comes from a legitimate source.
This is a mandatory check, and failure to provide a clear audit trail will bring your application to a grinding halt.
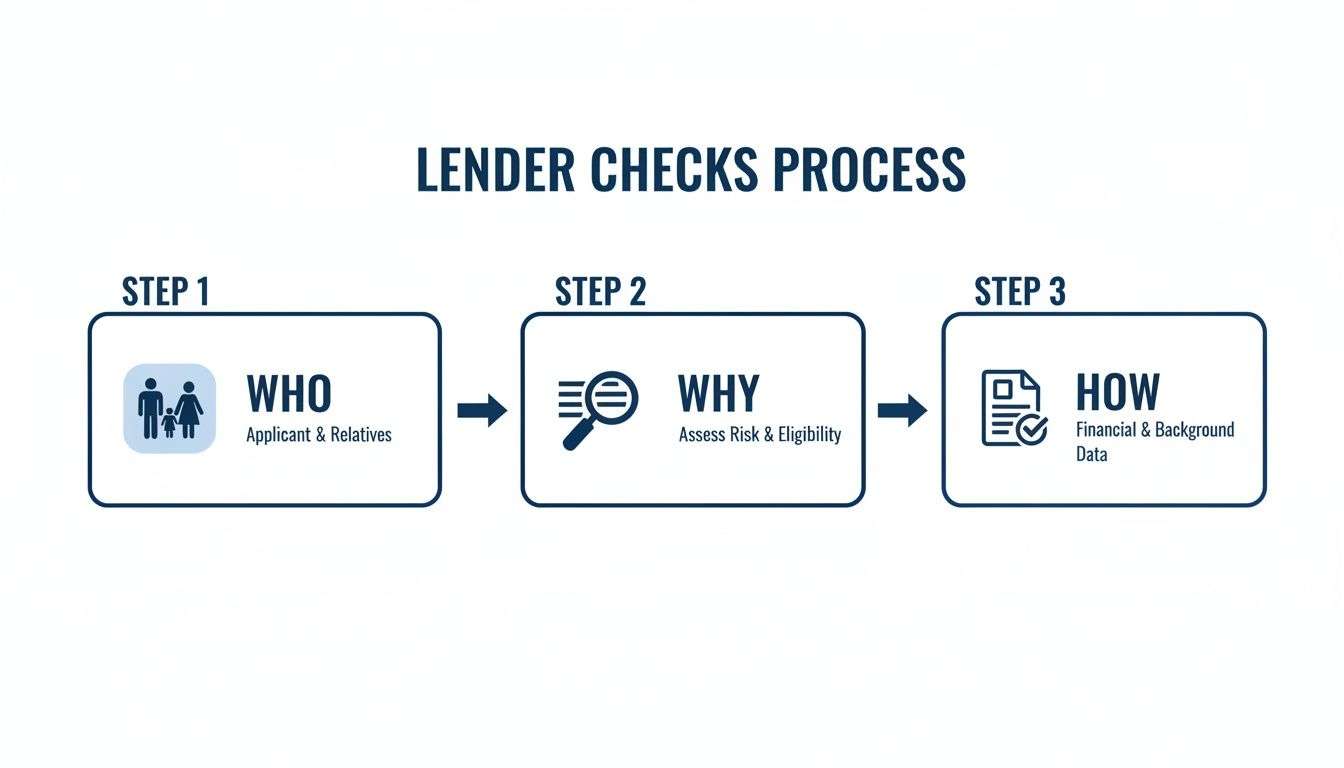
As the flowchart shows, the process is straightforward. It moves from the family member providing the gift (the WHO), to the lender’s need to assess risk (the WHY), and finally to you submitting the formal documents (the HOW). This structure protects everyone involved and keeps your gifted deposit mortgage application compliant.
Navigating Tax and Legal Implications
Receiving a financial gift is a fantastic boost to your home-buying dreams, but it is crucial to understand the tax and legal rules that come with it. These regulations are there to ensure fairness and prevent tax avoidance, so knowing the score protects both you and the person generously giving you the money. The big one to understand is Inheritance Tax (IHT).
In the UK, a large financial gift is officially known as a ‘Potentially Exempt Transfer’ (PET). It sounds a bit technical, but the idea is actually quite simple. It means the gift is potentially tax-free, but it all hinges on one thing: time.
If the person who gave you the money (the donor) lives for seven years after making the gift, it becomes completely exempt from IHT on their estate. This is what is widely known as the ‘seven-year rule’.
The Seven-Year Rule and Annual Allowances
The ‘seven-year rule’ is the cornerstone of how gifts are treated for Inheritance Tax. It is worth noting that any potential tax bill falls on the donor’s estate, not on you as the recipient, but it is a detail everyone involved should be crystal clear on. The clock starts ticking the moment the gift is made.
On top of this, everyone has an annual gift allowance. This lets an individual gift up to £3,000 each tax year without any IHT worries at all, even if they pass away within the seven years. This allowance can even be carried forward one year if it was not used, meaning a couple could potentially gift up to £12,000 in one go, completely tax-free.
If the gift exceeds the allowances and the donor sadly passes away within seven years, ‘taper relief’ applies, reducing the amount of tax owed over time.
| Years Between Gift and Death | Tax Paid |
|---|---|
| Less than 3 | 40% |
| 3 to 4 | 32% |
| 4 to 5 | 24% |
| 5 to 6 | 16% |
| 6 to 7 | 8% |
| 7 or more | 0% |
A Note on Deprivation of Assets
There is another legal point to be aware of, though it is less common in a straightforward gifted deposit mortgage scenario: ‘deprivation of assets’. This is where a local authority might look into a large financial gift if the donor later needs funding for social care.
“If a local authority believes money was deliberately given away to avoid paying for care fees, they can assess the donor as if they still had the money. This is why seeking professional advice is so important to protect everyone involved.”
For instance, if someone gifts a large sum for a house deposit in Chelmsford and then applies for care funding just a few months later, the council may question the timing. Genuine gifts made when the donor is healthy are rarely a problem, but this shows why careful planning is so important.
Given the complexities here, the best thing the person gifting the money can do is seek their own independent legal and financial advice. This ensures they fully understand the consequences of their generous gift and that everything is properly structured from the start.
Let Us Guide You to a Successful Mortgage
Navigating the world of gifted deposit mortgages can certainly feel complicated. From figuring out each lender’s specific rules to getting the paperwork just right, it is easy to feel a bit overwhelmed. That is where we come in.
With over 35 years of experience, we specialise in securing gifted deposit mortgages. We have deep, local knowledge of the Essex property market, from the growing communities in Chelmsford to the historic streets of Colchester. This allows us to find a mortgage that is right for you and your situation.
Why Choose an Expert Broker?
Going it alone often means you only see what the high-street banks are willing to offer. As whole-of-market brokers, we have access to hundreds of deals from major banks and specialist lenders you would not find on your own. This means we can pinpoint lenders who are much more flexible with gifted deposits, especially in more complex cases.
We take care of the entire process for you:
Finding the Right Lender: We will match you with lenders whose criteria you meet, saving you time and stress from failed applications.
Perfecting Your Paperwork: We check every document, from the gifted deposit letter to the proof of funds, to ensure it is spot-on before submission.
Removing the Stress: We handle the phone calls, chase the lenders, and keep your solicitor in the loop. You can focus on the exciting parts.
This dedicated support is especially valuable for first-time buyers new to the process. You can learn more about how we help new buyers in our dedicated guide for first-time buyer mortgage brokers.
Tailored Solutions for Your Situation
Whether you are a first-time buyer eager to get on the ladder, self-employed with complex finances, or looking to move home using a gift, we provide clear, straightforward advice. We always take the time to understand your personal and financial circumstances before recommending a path forward.
“Our role is to be your advocate. We use our expertise to translate the complexities of the mortgage world into a clear, manageable plan, giving you the confidence to move forward and secure your dream home.”
Think of us as your single point of contact. We are here to remove the uncertainty and hassle so you can focus on the most important part: finding and moving into your new home.
Frequently Asked Questions About Gifted Deposits
💡 Top Tip: Even if your entire deposit is a gift, having some of your own savings set aside can make you a much stronger applicant in a lender’s eyes. Some lenders will not accept a gifted deposit without the borrower contributing to the deposit as well.
Navigating a gifted-deposit mortgage for the first time naturally raises a lot of questions. We get it. To give you the confidence you need, here are some clear, straightforward answers to the most common queries we hear from buyers in and around Essex.
Can the Entire Deposit Be Gifted?
Absolutely. In most cases, lenders are perfectly happy for your entire deposit to come from a gift. It is a very common way for first-time buyers to get a foot on the property ladder, and many lenders have products designed for this exact situation.
That said, a small number of lenders might want to see that you have also saved some money yourself. It is less about the amount and more about demonstrating a history of saving, which they see as a good sign of financial responsibility. Our job is to find you the right lender whose criteria fit your circumstances perfectly.
What Happens If the Person Gifting the Deposit Dies Within Seven Years?
This is a really important question, and it all comes down to Inheritance Tax (IHT). If the person who gifted you the money (the donor) passes away within seven years of making the gift, that money could be considered part of their estate and become subject to IHT.
It is often called the ‘seven-year rule’, and the amount of tax due actually reduces on a sliding scale after the third year. Because the potential tax liability falls on the donor’s estate, not on you, we always strongly recommend that the person gifting the money obtain independent financial and legal advice before proceeding.
“A gifted deposit has no impact on your credit file. The gift itself is a private transaction. The only credit-related event is the formal mortgage application, where the lender performs a standard hard credit check.”
Can I Use a Gifted Deposit for a Buy-to-Let Property?
Yes, you can, but it is a bit more complicated. The pool of lenders who will accept a gifted deposit for an investment property is much smaller than for a standard residential purchase.
The ones who do often have stricter criteria. For instance, a lender might ask for a 25% deposit on a buy-to-let in Braintree and cap the gifted portion at just half of that total. They might also require you to be an existing homeowner. As specialists in the buy-to-let market, we know which lenders are open to this and can guide you through the tougher application process.
Does a Gifted Deposit Affect My Credit Score?
Not one bit. Receiving a gift of money is a private financial arrangement; it is not a credit event, so it has zero impact on your credit score or history.
The only part of the process that touches your credit file is when you formally apply for the mortgage. At that point, the lender will run a standard ‘hard’ credit check to assess your reliability as a borrower. The gift itself remains a confidential matter between you, the donor, and your mortgage lender.
Ready to turn that generous gift into the keys to your new home? Our team is here to make your homeownership dreams a reality. Contact us today to start your journey.





