
You’re probably here because you own a home, need to raise money, and your credit history is making every mainstream option feel shut. That’s a common situation in Chelmsford, Braintree, Colchester and across Essex. It’s frustrating, but it’s not hopeless.
💡 Top tip: focus on your equity and stable income, not just your credit score. That’s what specialist lenders look at first when a case has bumps. I’ll explain exactly why that matters later.
If you’re searching for second mortgage lenders with bad credit, the key point is simple. Bad credit doesn’t automatically kill the deal. It usually means you need the right lender, the right packaging, and a realistic view of pricing and paperwork.
Introduction: Getting Finance with a Less Than Perfect Past
Many homeowners think that bad credit means the conversation ends before it starts. That’s wrong. What it usually means is that the case moves away from a high-street bank and into the specialist lending market.
A second charge mortgage can be a practical fix when you’ve got a decent first mortgage rate you don’t want to lose, but you still need to borrow. That money might be for home improvements, debt consolidation, helping family, or creating breathing room.
Why this route exists
Mainstream lenders like clean, simple cases. If your file shows missed payments, defaults, a CCJ, or an old IVA, they often become cautious fast. A specialist second-charge lender looks at the case differently.
They’ll still care about your credit profile, but they’ll also ask more detailed questions about the property, your available equity, your income, and whether the situation that caused the past problem has been resolved.
Practical rule: if your income is stable and your property has enough equity, you may have far more options than you think.
That’s why I tell clients not to obsess over the score alone. The score matters, but it isn’t the whole story. In this part of the market, lenders want to understand risk, not just reject it.
What borrowers get wrong
The biggest mistake is applying too early with poor paperwork. The second biggest is assuming every lender views bad credit the same way. They don’t.
Some lenders will tolerate historic problems if recent conduct is clean. Others will focus heavily on how much equity you’ve got left after the new loan. Others want a stronger written explanation before they’ll even take the case seriously.
If you approach this properly, you’re not asking a lender to ignore your past. You’re showing them why lending to you now still makes sense.
What Is a Second Charge Mortgage for Bad Credit
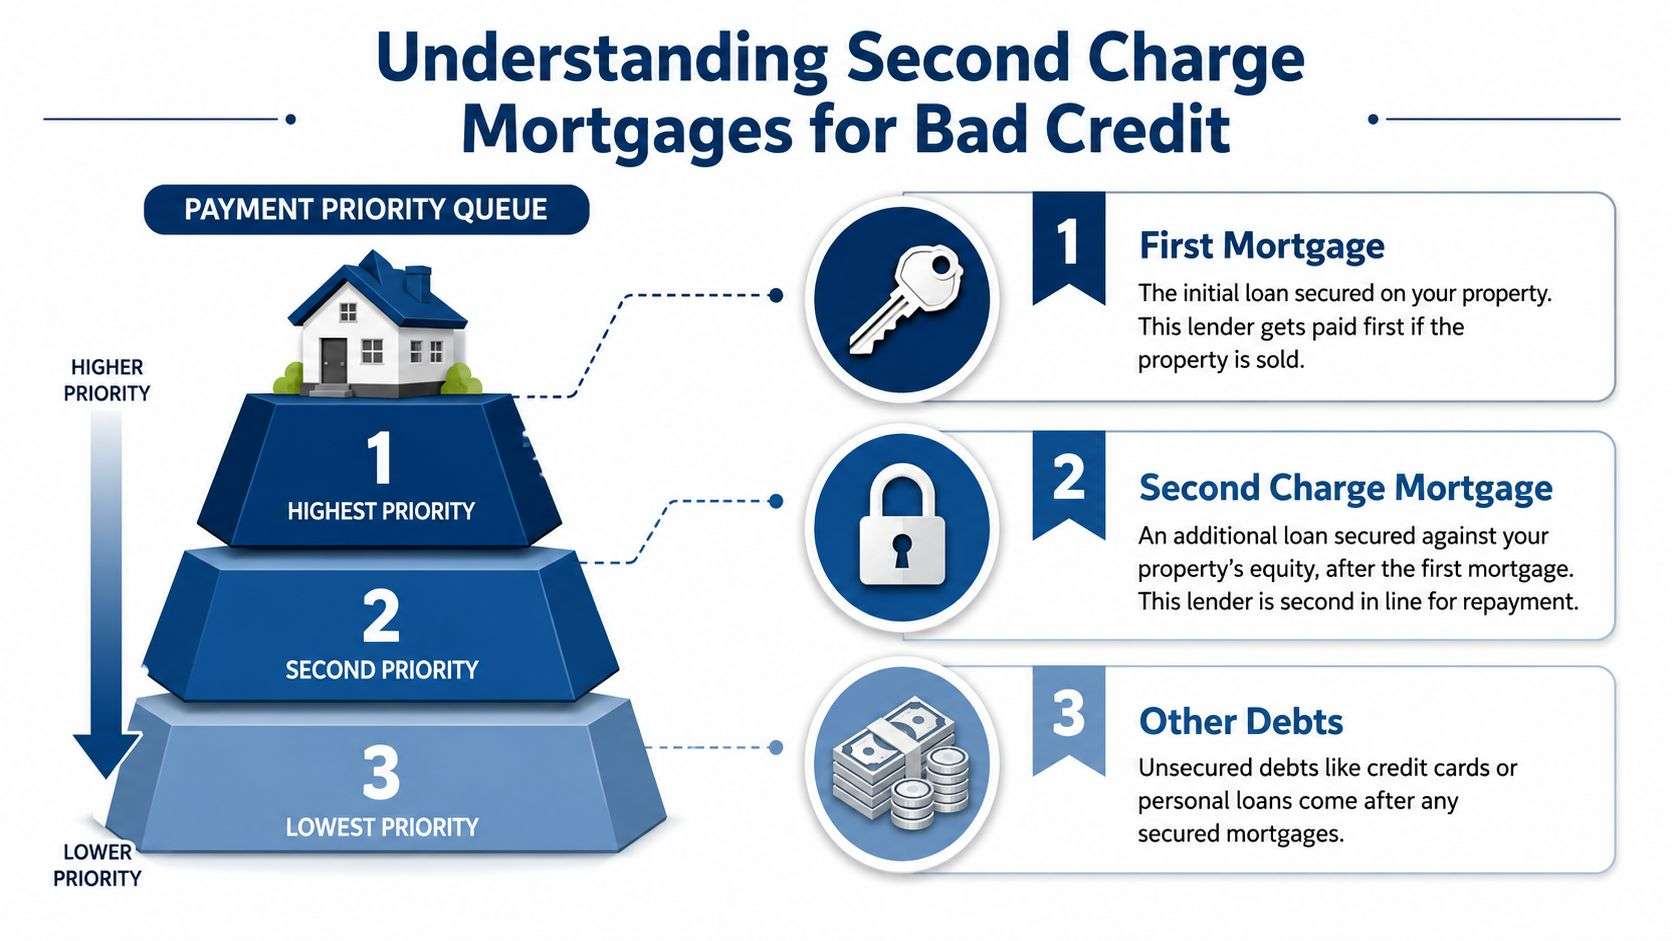
A second charge mortgage is another loan secured against your home, sitting behind your existing mortgage. Think of it as a payment queue. Your first mortgage lender stands at the front. The second charge lender stands behind them.
If the property ever had to be sold due to default, the first lender would be paid first. The second charge lender only gets repaid after that. That’s the whole reason this lending is treated as higher risk.
Why equity matters more than people realise
The technical risk here is driven by the combined loan-to-value ratio, often abbreviated as CLTV. Lenders need sufficient remaining equity because the second lender sits behind the first in priority and is repaid only after the first if repossession occurs. That’s also why pricing is higher and why bad-credit cases are often only considered when equity is strong. Industry guidance typically cites minimum equity buffers of 15% to 20%, according to Bankrate’s explanation of second mortgages.
That one point explains a lot. If your credit is bruised but your equity is healthy, you’re much easier to place. If your credit is bruised and your equity is thin, options narrow quickly.
Why not just ask your current lender
Many borrowers first try to take out a further advance from their existing lender. That’s sensible in theory. In practice, if your credit file has deteriorated since you took the first mortgage, that lender may say no.
That’s where specialist second charge lending comes in. It exists for cases that don’t fit standard high-street policy. Lenders active in this space include UTB, Pepper Money and Shawbrook. That doesn’t mean they say yes to everyone. It means there is a live market for borrowers with adverse credit.
The right lender isn’t the one with the flashiest advert. It’s the one whose criteria match your exact credit issue, income type and level of equity.
A second charge mortgage isn’t a loophole. It’s a structured lending solution for people whose cases need a more nuanced underwriting approach.
How Your Credit History Realistically Affects an Application
Let’s be blunt. Your credit history changes the price, the paperwork and the lender pool. It doesn’t always stop the application, but it absolutely changes how it’s assessed.
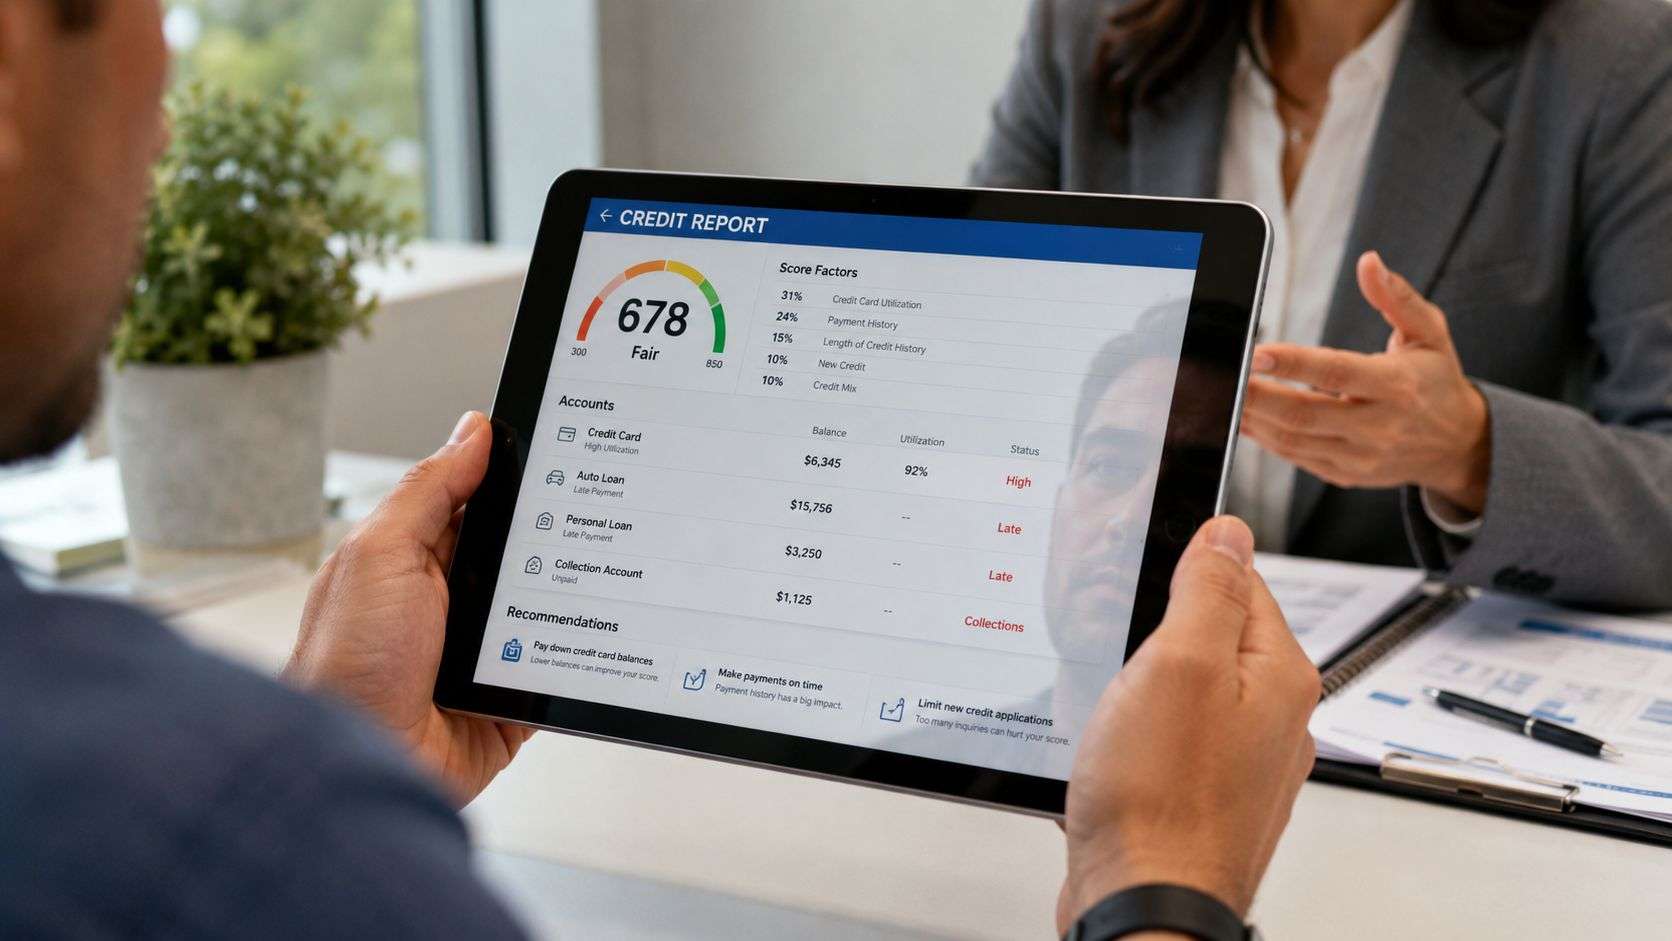
If your file shows missed payments, defaults, CCJs or an IVA, lenders will want context. They’ll look at whether the issue was recent or older, whether it was a one-off or part of a wider pattern, and whether your current bank conduct shows stability.
What does bad credit usually mean in practice?
It usually means specialist pricing. From broker experience, rates tend to be 1% to 3% more expensive than high-street options, depending on the amount borrowed, the credit record, and the overall loan-to-value ratio once the current mortgage and new loan are combined.
It also means stronger affordability checks. Lenders want proof that the payment is manageable now, not just theoretically affordable on paper. If you’re already reviewing your options, this guide to getting a mortgage with bad credit is worth reading alongside a second-charge borrowing guide.
What underwriters actually look for
Underwriters don’t just scan for problems. They look for signs that the problem is contained.
Stable income: regular employed income, steady self-employed drawings, or reliable pension income helps calm a nervous case.
Clean recent conduct: if the old issue is behind you and current commitments are up to date, the file reads far better.
A sensible reason for borrowing: lenders are more comfortable when the purpose is logical and clearly evidenced.
Good bank statements: if your statements are chaotic, the lender assumes your finances are too.
Advisor view: a messy bank statement can do more damage than a historic blip that’s already been explained.
Consider this. You’re asking a lender to accept more risk than a prime borrower presents. In return, they’ll charge more and ask more questions. That’s the trade.

Typical Criteria from Specialist Second Mortgage Lenders
If you want a realistic sense of where the market starts, there are some broad benchmarks worth knowing. Widely used industry benchmarks for second mortgages cluster around a minimum credit score of about 620 to 680, 15% to 20% home equity, and a debt-to-income ratio near 43%. Borrowers below those levels are usually treated as higher risk and face tighter underwriting, based on Rocket Mortgage’s overview of second mortgages.
Those figures are not universal lender rules. They are useful benchmarks. In practice, one lender may flex on score but be stricter on equity. Another may tolerate a rougher file if the income is straightforward and well evidenced.
Typical Specialist Lender Criteria for Second Mortgages
| Criteria | What Lenders Look For | Typical Minimum | EHF Mortgages Tip | Importance |
|---|---|---|---|---|
| Credit profile | Overall conduct, severity of issues, whether problems are historic or ongoing | About 620 to 680 benchmark | Don’t hide adverse credit. Declare it early and explain it clearly | High |
| Home equity | Enough value left in the property after the first mortgage and new loan | Around 15% to 20% equity | Check the likely combined borrowing before you apply | High |
| Affordability | Income versus existing credit commitments and the new payment | Debt-to-income near 43% benchmark | Reduce avoidable monthly commitments before application if you can | High |
| Income type | Employed, self-employed, retired, contract or mixed income | No single universal minimum stated | Make income evidence consistent across payslips, statements and tax documents | Medium |
| Property and purpose | Standard property, acceptable loan purpose, sensible exit | Case by case | If the purpose is unusual, document it properly from the start | Medium |
What strengthens a case
A strong application isn’t just about ticking criteria boxes. It’s about reducing doubt.
If you’re working on fixing your credit score realistically, do it with your eyes open. Small clean-ups help, but second-charge lenders still care more about the full story than a cosmetic jump in score.
For borrowers comparing options, it also helps to understand how a specialist adverse credit mortgage lender tends to assess complicated cases.
“The single most important document is a clear, honest letter explaining your past credit problems and what has changed since. It turns you from a credit file into a person, and that’s what persuades an underwriter.”, EHF Mortgages Advisor
What weakens a case fast
Missing explanations: if a lender spots adverse credit before you explain it, trust drops immediately.
Incomplete paperwork: lenders assume the worst when documents are missing or inconsistent.
Recent financial chaos: gambling markers, bounced payments and overdrafts all create problems.
Unclear borrowing purpose: if the loan reason sounds vague, the file gets tougher.
This is why broker packaging matters. The same borrower can look lendable or unlendable depending on how the case is presented.
Your Step-by-Step Application and Document Checklist
If you want a result, get organised before the application goes in. Good second charge cases are built, not rushed. Whether you’re in Braintree, Chelmsford or elsewhere in Essex, the preparation phase is where deals are won or lost.
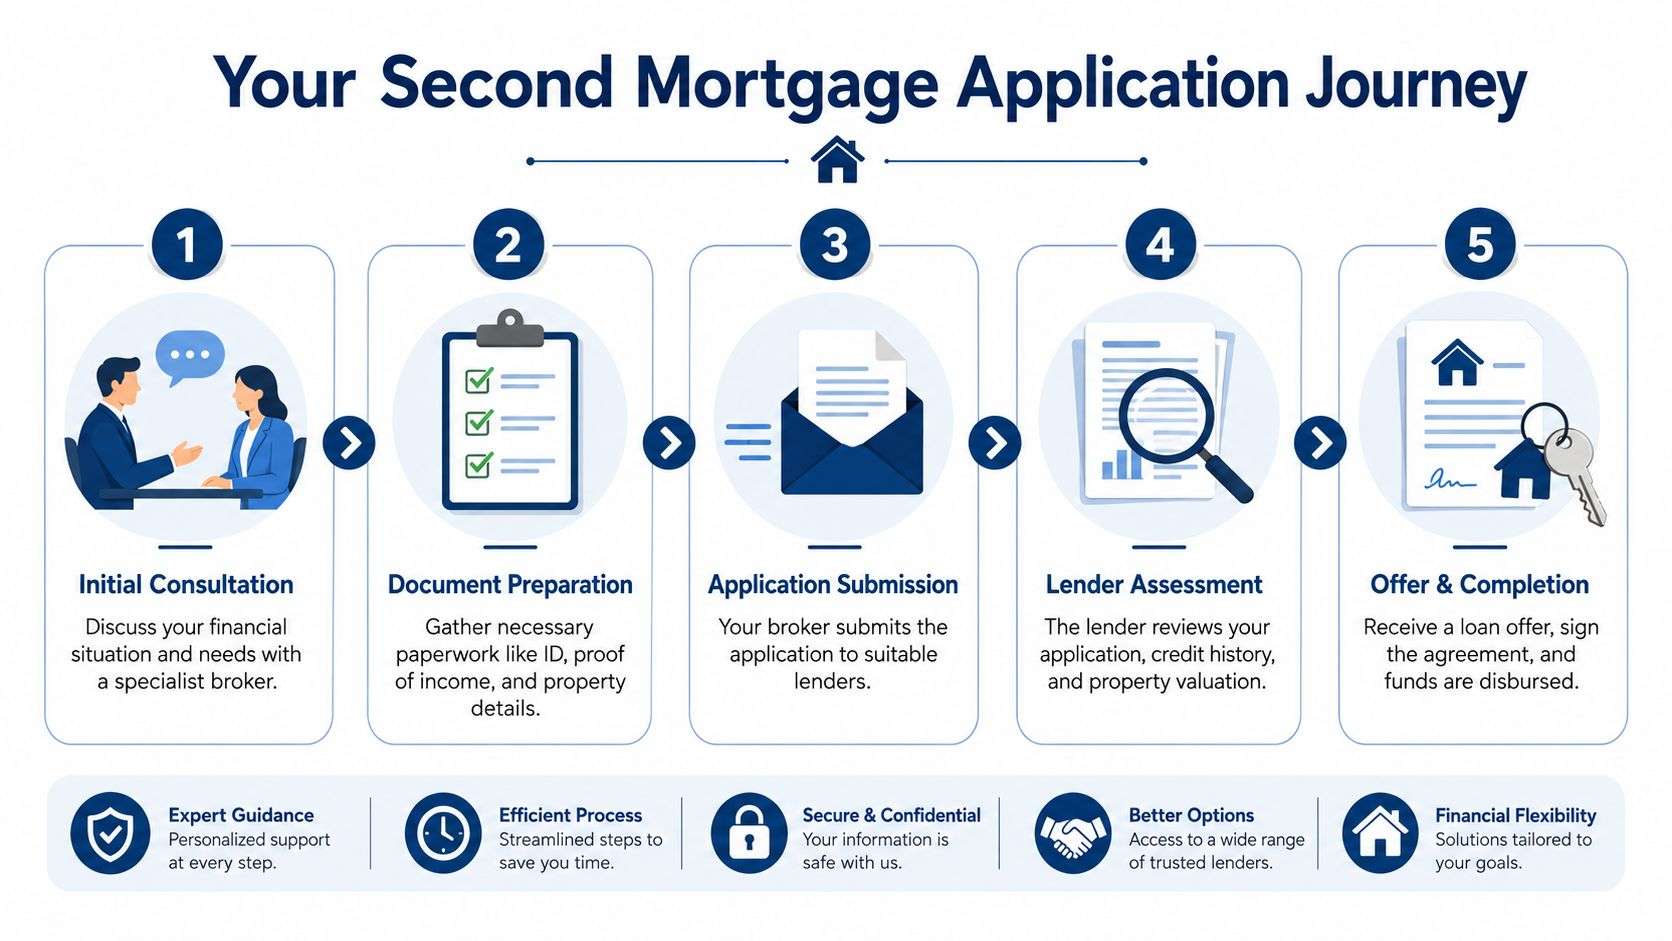
Start by discussing the case properly with a broker who understands adverse credit. Not someone who only knows standard residential mortgages. You need someone who can match your profile with lenders operating in this part of the market.
Step one: get document-ready
This sounds basic, but it’s where most applicants fall short. Specialist lenders expect a complete picture.
Bring these first:
Proof of income: payslips, accounts, SA302s or pension evidence, depending on how you earn.
Bank statements: these need to support the story your application tells.
Your credit report: not a vague memory of it. The actual report.
Mortgage details: your current balance, monthly payment and lender.
Reason for borrowing: clear, sensible and consistent.
If your documents don’t line up, the lender won’t assume it’s a harmless mistake. They’ll assume the case needs more scrutiny.
Step two: Write the explanation letter properly
This letter matters more than people think. It should be honest, brief and specific.
Don’t write an emotional essay. Don’t blame everyone else. Don’t pretend the issue wasn’t serious if it was.
A good letter covers:
What happened
State the problem plainly. Redundancy, illness, separation, business disruption or another genuine cause.When it happened
Give the timing clearly so the lender can place it in context.What changed
Explain why the situation is now different. New job, settled accounts, stronger household income, or improved financial control.Why the new borrowing makes sense
Connect the purpose of the second charge to your current circumstances.
That letter turns a cold file into a coherent application.
Here’s a simple explainer if you prefer to see the process visually.
Step three: Submit to the right lender first
This is where experience matters. You don’t want unnecessary declines on your record because someone guessed badly.
A broker should review the adverse credit, the equity position, the income structure, and the property, then choose lenders whose criteria are compatible. The first submission should be targeted, not hopeful.
Step four: Expect valuation and underwriting questions
Once submitted, the lender will review the paperwork and assess the property. They may ask for extra documents or clarification. That’s normal.
Don’t panic if they come back with questions. In this market, questions aren’t always a bad sign. Silence is often worse.
Step five: Stay disciplined until completion
Keep your bank account clean. Don’t take new credit. Don’t miss existing payments. Don’t move money around in ways that make no sense.
A case can be unravelled late if your conduct changes during the assessment. Lenders want consistency from application through to completion.
Understanding the Risks, Costs, and Alternatives
Your home may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.
That warning isn’t boilerplate. It’s the central risk. A second-charge loan is secured against your home, so you need to take the decision seriously.
Costs people forget about
The rate matters, but it isn’t the whole cost. You also need to check:
Arrangement fees: Some products include lender fees
Valuation fees: the property still needs assessing
Broker fees: ask what you’re paying and when
Legal costs: some cases involve extra legal work
Early repayment terms: useful to understand before you sign
If you’re comparing products, review current second charge mortgage rates alongside the full fee picture, not as a standalone number.
Alternatives worth considering
A full remortgage can work if the first charge rate and your credit profile make it sensible. An unsecured loan may suit smaller borrowing if affordability is strong. For property investors looking at short-term asset-based funding instead, this guide to hard money loans for investors gives useful context on how a very different type of lending works.
A second charge isn’t automatically the best answer. It’s the best answer when it solves the problem without wrecking your existing mortgage position.
If your current first mortgage is strong and replacing it would cost more overall, a second charge often deserves a hard look.
Frequently Asked Questions
Can I get a second-charge mortgage with a recent CCJ?
Possibly, yes. It depends on the wider case. A recent CCJ makes the application tougher, but lenders will still look at equity, income stability, current conduct and how well the issue is explained. If you’re in Colchester or nearby, local broker support can make a big difference because the packaging needs to be spot on.
How much can I borrow?
There isn’t one universal answer. The lender will look at your available equity, your income, your existing commitments and the purpose of the loan. Borrowers often focus on the maximum. I’d focus on the amount that solves the problem without stretching affordability.
Will applying damage my credit score?
Any credit application can leave a footprint, which is why scattergun applications are a bad idea. That’s another reason to avoid applying directly to several lenders at once. A properly filtered application is better than multiple failed attempts.
Is a specialist lender always expensive?
Usually more expensive than prime borrowing, yes. But expensive doesn’t always mean wrong. If the loan lets you keep a strong first mortgage rate, consolidate the right debts, or fund necessary works, the overall outcome can still be sensible.
If you’ve read this far, you probably need proper answers rather than guesswork. Speak to EHF Mortgages for specific advice on whether a second charge is realistic in your situation, then take the next step through the Contact Us page.





