
Stepping onto the property ladder is a massive milestone, and it’s completely normal for it to feel both incredibly exciting and a little daunting.
💡 Top Tip: Get yourself ‘mortgage-ready’ before you even start looking at properties. This single piece of advice is the biggest advantage you can give yourself in the home-buying process, and we’ll explain exactly what it means later in this guide.
Your Guide to Homeownership in 2026
Guide Contents
Think of this guide as your personal roadmap to securing a first-time buyer mortgage. Our goal is to take the confusion out of the process and replace it with confidence. We’ll walk you through everything, step-by-step, from figuring out your deposit to finally getting those keys to your new home in Chelmsford, Colchester, or wherever you’ve set your sights.
As you get started on this exciting new chapter, having a plan is invaluable. A comprehensive checklist for your first house can be a brilliant tool for keeping you organised and breaking everything down into manageable chunks.
“The path to owning your first home is a marathon, not a sprint. Preparation and expert guidance are the two things that will get you over the finish line successfully.”
Whether you’re just putting your first savings aside or you’re ready to start making applications, the information ahead will give you the clarity you need to move forward. Your journey to owning a home in Essex starts right here.
What Is a First-Time Buyer Mortgage?
First things first, let’s bust a common myth. There’s no secret, special product called a “first-time buyer mortgage.” The term refers to a standard mortgage taken out by someone who has never owned property, whether here in the UK or abroad.
Think of a mortgage as a very large, long-term loan from a bank or building society that lets you buy a home. The property you’re buying acts as security for that loan, which means the lender could repossess it if you can’t keep up with your repayments.
Because first-time buyers are new to the whole process, lenders are keen to win their business. They often put together specific deals with attractive features, such as lower deposit requirements or cashback when you take possession.
Understanding The Core Mortgage Terms
Getting your head around the lingo is the first step to feeling in control of your home-buying journey. These are the fundamental building blocks of any mortgage deal you’ll come across.
- Principal: This is the total amount of money you borrow to buy your home. So, if you’re buying a £250,000 house in Braintree and you’ve saved a £25,000 deposit, your principal is £225,000.
- Interest: The lender’s charge for lending you the money, expressed as a percentage. It’s basically the cost of borrowing.
- Term: This is the length of time you have to pay back the loan in full. For most first-time buyers, a typical mortgage term is between 25 and 35 years.
The role of first-time buyers in the market is only getting bigger. Projections show that first-time buyers are on track to account for 39% of all home purchases in the UK during 2025, making them the largest single group of buyers. This reflects a huge 20% year-on-year increase, partly thanks to better mortgage availability in affordable areas like Essex. You can dive deeper into the analysis of these first-time buyer trends on Financial Reporter.
“Understanding these basics is crucial. It’s like learning the rules of a game before you start playing; it gives you the confidence to make smarter decisions.”
Fixed-Rate Versus Variable-Rate Mortgages
One of the biggest choices you’ll make is what kind of interest rate you want. This decision directly impacts how much you pay each month, so it’s a biggie.
| Rate Type | How It Works | Best For | Key Consideration |
|---|---|---|---|
| Fixed-Rate | The interest rate is locked in for a set period, usually 2, 3, or 5 years. This means your monthly payment stays the same. | Buyers who want payment certainty and need to budget carefully without any surprises. | You won’t benefit if interest rates happen to fall during your fixed term. |
| Variable-Rate | The interest rate can go up or down, often tracking the Bank of England’s base rate. This means your payments can change. | Buyers who are comfortable with a bit of risk and have a feeling that rates might fall. | Your monthly payments could increase, making budgeting much harder. |
Grasping these concepts is your foundation for navigating the world of mortgages. With this knowledge under your belt, you can start to figure out which products and deals are the right fit for your financial situation.
Decoding Deposits And Lender Affordability Checks
Getting your first mortgage really boils down to two big milestones: saving up a decent deposit and then convincing a lender you can afford the repayments. The two are completely intertwined, and getting your head around how they work together is the first major step towards a successful application.
Think of the deposit as your stake in the game – it’s the chunk of the property’s price you pay upfront from your own savings. While it’s technically possible to get a mortgage with just a 5% deposit, pushing for more, say 10% or higher, makes a world of difference. It shows the lender you’re serious and less of a risk.
The Power Of Loan-To-Value (LTV)
Lenders have a simple way to measure their risk: the Loan-to-Value (LTV) ratio. It’s just the percentage of the property’s value you’re asking them to lend you. A bigger deposit means a smaller loan and, therefore, a lower LTV. That simple shift almost always unlocks better, cheaper interest rates.
To see this in action, let’s look at how your deposit changes the numbers for a typical first-time buyer property in Chelmsford.
How Your Deposit Affects Your Mortgage
This table breaks down how different deposit sizes impact the LTV for a £300,000 property, a common price point for first-time buyers in Essex.
| Property Price | Deposit Percentage | Deposit Amount | Mortgage Amount | Loan-to-Value (LTV) |
|---|---|---|---|---|
| £300,000 | 5% | £15,000 | £285,000 | 95% |
| £300,000 | 10% | £30,000 | £270,000 | 90% |
| £300,000 | 15% | £45,000 | £255,000 | 85% |
As you can see, saving that extra 5% or 10% does more than reduce your loan size; it makes you a much more attractive prospect to lenders, opening the door to better deals and lower monthly payments. For a deeper dive, check out our complete guide on the minimum deposit needed for a house.
Scraping that deposit together is no small feat, especially when you factor in regional price differences. The average first-time buyer property in the UK hit £311,034 in 2024, but in our part of the world (East of England), that figure jumps to £346,523. It’s a perfect example of why getting local, expert advice is so valuable.
How Lenders Assess Your Affordability
Once the deposit is sorted, the lender puts your finances under the microscope with a detailed affordability assessment. This isn’t a simple back-of-the-envelope calculation based on your salary anymore. It’s a forensic look at your financial life to ensure you can handle the repayments, even if interest rates rise.
Here’s what they’ll be looking at:
- Your Income: They’ll start with your basic salary but will also consider consistent bonuses, commission, or overtime. They want to see a stable earnings history.
- Your Outgoings: This covers all your financial commitments. Think credit card balances, personal loans, car finance, and student loans.
- Your Spending Habits: Lenders will ask for your last three to six months of bank statements to get a feel for your day-to-day spending on things like holidays, takeaways, and nights out.
“Lenders aren’t trying to catch you out; they’re trying to build a picture of financial responsibility. A clean bank statement showing regular saving and sensible spending is one of your most powerful tools.”
Beyond your own finances, a lender’s decision will also be influenced by the wider economic climate. Understanding factors that affect the market, like Mortgage Rates In America, can be useful, as global trends often have a knock-on effect on UK rates. Ultimately, taking a few months to pay down debts and budget carefully before applying can be the single most important thing you do to get that ‘yes’ from a lender.
UK Government Schemes for First-Time Buyers
Navigating the property market for the first time can feel like you’re trying to scale a mountain, but you don’t have to go it alone. The UK Government has put several schemes in place specifically to give first-time buyers a leg-up, making that first step onto the property ladder feel much more within reach.
These aren’t just handouts; they’re structured programmes designed to tackle the biggest hurdles, like saving for a massive deposit. For buyers in areas like Essex, where house prices can be a real challenge, understanding these schemes is the key to unlocking your home-owning potential.
Shared Ownership: Getting Your Foot In The Door
One of the most popular routes for first-time buyers is the Shared Ownership scheme. It’s a clever way to get on the ladder without buying a whole property at once. Instead, you purchase a share you can afford – usually between 25% and 75% of the home’s full value – and pay a subsidised rent on the rest to a housing association.
This approach brings two massive benefits:
- A smaller deposit: Because you’re only buying a share, your deposit is based on that share’s price, not the full property value. This dramatically lowers the initial savings goal.
- A smaller mortgage: You only need a mortgage to cover your share, which means a smaller loan and more manageable monthly payments.
The great thing is, you’re not stuck with just a share forever. Over time, you can buy more shares in your home through a process called ‘staircasing’. You can eventually build up to owning 100% if you want to. It’s a fantastic option for people in towns like Braintree who have a steady income but haven’t yet saved a huge deposit.
Lifetime ISA: Supercharge Your Savings
The Lifetime ISA (LISA) isn’t so much a home-buying scheme as it is a powerful savings tool with a huge government-backed perk. It’s designed to help you save for either your first home or for retirement, and it’s a bit of a no-brainer if you’re eligible.
Here’s how it works for getting on the property ladder:
- You can open one if you’re aged between 18 and 39.
- You can put away up to £4,000 each tax year.
- The government then adds a 25% bonus on top of whatever you save, up to a maximum of £1,000 per year.
That’s essentially free money towards your deposit. If you manage to save the maximum £4,000, you’ll end the year with £5,000. Do that for a few years, and that bonus really starts to add up, seriously speeding up your journey to hitting your deposit target.
“Government schemes are there to bridge the gap between aspiration and reality. They provide a structural advantage that can turn a distant dream of homeownership into a tangible plan.”
Other Support for First-Time Buyers
While the main schemes have evolved over the years, it’s always worth being aware of all the support out there. The well-known Help to Buy Equity Loan scheme closed to new applications back in 2022, but its successor, the Mortgage Guarantee Scheme, is still going. This scheme encourages lenders to keep offering 95% LTV mortgages, helping those with smaller deposits.
This table breaks down the two main options currently available.
| Scheme | Who It Is For | Key Benefit | Main Consideration |
|---|---|---|---|
| Shared Ownership | First-time buyers who can’t afford to buy a home on the open market. | Buys a share (25-75%), requiring a much smaller deposit and mortgage. | You’ll pay rent on the portion of the property you don’t own. |
| Lifetime ISA (LISA) | UK residents aged 18-39 saving for their first home or retirement. | A 25% government bonus on savings, up to £1,000 extra per year. | The funds must be used for a first home purchase or retirement after 60. |
These schemes can be an absolute game-changer, but the rules and eligibility criteria can be tricky to navigate. Getting expert advice is the best way to make sure you understand all the details and choose the right path for your situation.
Your Step-By-Step Mortgage Application Journey
The mortgage application process can feel like a daunting maze, but it’s actually a series of clear, manageable steps. Think of it as a roadmap. Once you understand each milestone, you can move forward with confidence and leave the stress behind.
Let’s break down the entire journey, from those first tentative checks right through to the moment you finally get your hands on the keys. Knowing what’s coming transforms an overwhelming task into a straightforward plan, ensuring you’re ready for whatever the lender asks.
From Initial Checks To A Formal Offer
The first part of your journey is all about laying solid groundwork and showing lenders you’re a reliable borrower. It actually starts long before you find that dream home in Colchester or Chelmsford.
- Financial Assessment and Decision in Principle (DIP): Before anything else, a mortgage adviser will comb through your finances to figure out how much you can realistically borrow. With that number sorted, you can get a Decision in Principle (DIP). This is a lender’s certificate stating they’re likely to lend you a certain amount, and it’s gold dust for showing estate agents you’re a serious contender.
- Making an Offer and Full Application: DIP in hand, you can make an offer on a property with real confidence. Once it’s accepted (congratulations!), it’s time to submit your full mortgage application. This is where things get serious, and you’ll need to provide all your financial documents.
- Underwriting and Valuation: Now, the lender’s underwriting team takes the reins. They’ll do a deep dive into your application, meticulously verifying your income, outgoings, and credit history. At the same time, they’ll arrange a valuation of the property to make sure it’s worth the price you’ve agreed to pay.
- Receiving Your Mortgage Offer: If the underwriter is happy and the valuation comes back as expected, the lender will issue your formal mortgage offer. This is the legally binding document that details all the terms of your loan. You’ve done it – your mortgage is secured!
This simple infographic sums up the main stages perfectly, from getting that initial green light to finally picking up the keys.
As you can see, getting that DIP is the essential first move. It empowers you to make a credible offer, which is the stepping stone to the final prize: homeownership.
The Final Legal Steps To Completion
Once your mortgage offer is in the bag, the final phase is handled by solicitors in a process called conveyancing. This is where all the legal nuts and bolts are tightened, and the property’s ownership is officially transferred to you.
Your solicitor handles exchanging contracts with the seller’s solicitor, which is the point of no return – the deal becomes legally binding. They’ll then agree on a completion date. On this day, the lender releases the funds, you pay any outstanding costs, and the keys to your new home are officially yours. To get a better idea of how long all this takes, you can learn more about how long a mortgage application typically takes.
“The key is preparation. Having your documents ready and understanding each stage removes stress and prevents costly delays.”
The market for first-time buyer mortgages is looking particularly bright. Projections show that in 2025, first-time buyer mortgage deals are expected to climb to 390,324 in the UK – a huge 18% jump from 2024.
This growth is being driven by improving affordability and falling interest rates, making homeownership a realistic goal again for so many. It’s a trend we’re seeing right here in Essex, where firms like EHF Mortgages are guiding buyers through the process every day. Discover more about this projected rise in first-time buyer numbers from YBS.
Why A Mortgage Broker Is Your Greatest Asset
Remember that top tip from the start of this guide? 💡 We said getting ‘mortgage ready’ before you even look at properties is your biggest advantage. Now, let’s get into why an expert mortgage broker is the key to making that happen.
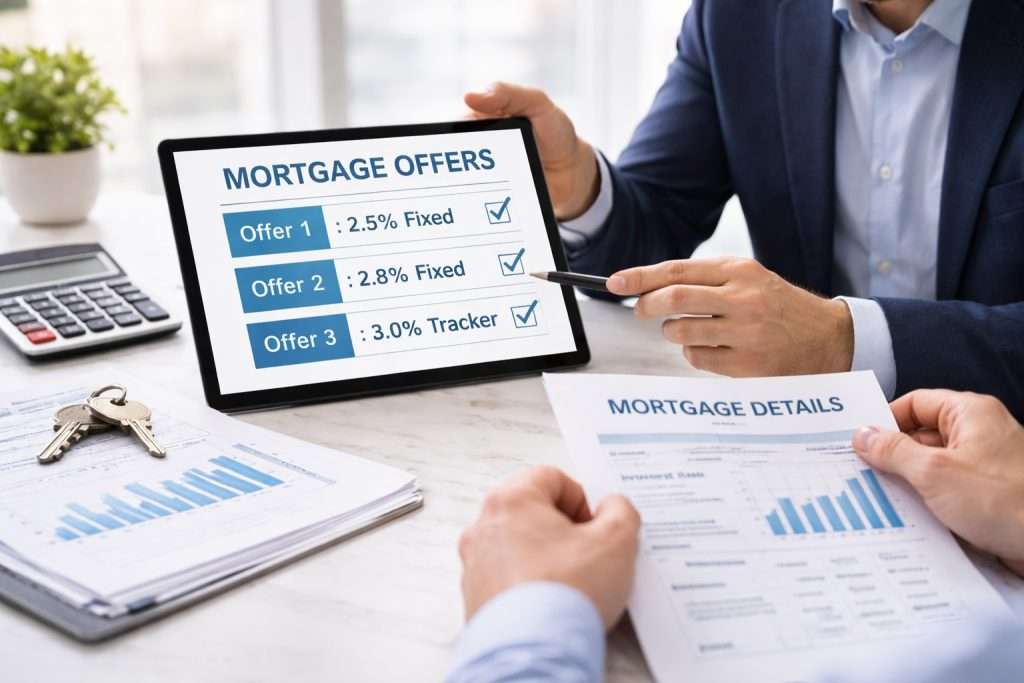
When you’re looking for first-time buyer mortgages, you basically have two paths: go directly to a high street bank or use a mortgage broker. While going direct might seem simpler, it has one massive drawback – a bank can only ever offer you its own products.
Think of it like this: it’s like going to a Ford dealership when you want to buy a car. They’ll only show you Fords. A whole-of-market mortgage broker, like us at EHF Mortgages, is different. We’re not tied to any single lender; we work for you.
Access To The Whole Market
Our job is to scan the entire mortgage market to find the best possible deal for your unique situation. We have access to hundreds of deals from a huge range of lenders, including the big high street banks, smaller specialist lenders, and even broker-exclusive rates you can’t find on your own.
This puts you at a massive advantage. Instead of spending endless hours comparing deals yourself, we do all the legwork. We sift through the noise and present you with the best options, taking the stress and guesswork out of the equation.
“A good broker doesn’t just find you a mortgage; they manage the entire process to get you the keys to your new home.”
Think of us as your personal project manager for the biggest financial decision of your life. We handle the paperwork, chase the lenders, and liaise with solicitors to ensure everything runs as smoothly as possible, from application to completion. For a deeper dive on what to look for, you might find our guide on how to choose a mortgage broker useful.
Expertise For Complex Situations
Not every first-time buyer has a straightforward application. What if you’re self-employed with a complex income, or you’ve had a few credit blips in the past? This is where a broker becomes absolutely invaluable.
We know which lenders are more flexible with self-employed income or which ones have more lenient criteria for minor credit issues. This inside knowledge can be the difference between getting a mortgage approval and a frustrating rejection. With over 35 years of local experience in Chelmsford and across Essex, we’ve built strong relationships with lenders and understand exactly what they’re looking for.
The benefits really are clear and tangible.
| Benefit | Going Direct To A Bank | Using A Broker (Like EHF) |
|---|---|---|
| Choice | Limited to that one bank’s products. | Access to hundreds of deals from many lenders. |
| Time | You must do all the research and paperwork. | We handle the entire process for you. |
| Cost | You may not get the most competitive rate. | We find the best deal, potentially saving you thousands. |
| Expertise | Limited help for non-standard situations. | Specialist knowledge for complex cases. |
Our service always starts with a free, no-obligation chat where we get to know you and your goals. We want to be your long-term financial partner, guiding you not just through your first purchase but also through future remortgages and financial protection.
Common Questions From First-Time Buyers
To wrap things up, let’s tackle some of the most common questions we hear from first-time buyers. These are the practical, real-world concerns that are probably rattling around in your head as you think about what’s next.
We’ve kept the answers short and to the point, cutting through the jargon. While this is a great starting point, remember that the best advice is always tailored to you and your specific situation.
Realistically, How Much Can I Borrow?
There’s no magic number here because lenders are looking at your entire financial picture. You might hear a rule of thumb about borrowing 5 to 6 times your annual salary, but that’s a very old-school way of thinking. Today’s affordability checks are far more sophisticated.
Lenders will perform a deep dive into your income versus your fixed outgoings – things like car loans, credit card balances, and student loans. They also “stress test” your finances to see if you could still manage the repayments if interest rates were to climb. The final figure they offer will depend on your credit history, the amount of your deposit, and your overall financial health.
What Other Fees Are Involved Besides The Deposit?
The deposit is definitely the biggest hurdle, but it’s certainly not the only cost you need to plan for. Budgeting for these extra fees is absolutely critical if you want to avoid nasty surprises just when you’re about to get the keys.
Here are the main costs to get on your radar:
- Solicitor/Conveyancing Fees: This covers all the legal work required to transfer the property from their name to yours.
- Valuation Fee: The lender charges this to have the property valued, ensuring it’s worth what you’re paying for it.
- Arrangement Fee: Some of the best mortgage deals come with a fee for setting up the loan. This can sometimes be added to the mortgage itself.
- Stamp Duty Land Tax (SDLT): This is the government’s tax on buying property, though thankfully, first-time buyers often get a discount or don’t have to pay it at all, depending on the purchase price.
- Broker Fees: Some mortgage brokers will charge a fee for their service (at EHF, we’re transparent about this from the start).
- Moving Costs: Don’t forget the practical side! Budget for removal vans and all the little bits needed to get settled in.
“Thinking beyond the deposit is crucial for a smooth home-buying journey. A well-prepared budget that accounts for all associated costs removes last-minute financial stress.”
How Important Is My Credit Score?
In a word: vital. Your credit score is one of the first things a lender looks at when you apply for a first-time buyer mortgage. It’s their window into how you’ve handled money in the past. A healthy score shows them you’re a reliable borrower, which opens the door to better interest rates and gives you more lenders to choose from.
Even small blips from years ago can have an impact, so it’s always a smart move to check your credit report before you start. You can get a copy from agencies like Experian, Equifax, or TransUnion. This gives you a chance to spot any errors and improve your score if it needs a boost.
NB: Grab a 7-day trial of CheckMyFile, the only report that provides your credit details on all 3 agencies – Click Here at CheckMyFile
Is It Still Possible to Get A 5% (Or Less) Deposit Mortgage?
Yes, absolutely. Mortgages with a 5% deposit are very much alive and well. They’re often called 95% LTV (Loan-to-Value) mortgages and are specifically designed to help people get a foot on the property ladder without a massive upfront sum.
There are a growing number of 100% LTV Mortgage options, ideal for those struggling to save a deposit. Often, these lenders will require additional security to cover the increased risk of no deposit, but with new mortgage schemes launching every week, you may find the options are ideal for you.
The trade-off is that they usually come with slightly higher interest rates than mortgages with a larger deposit. Lenders see them as carrying a bit more risk, and the higher rate reflects that. For this reason, having a squeaky-clean credit history becomes even more important when you’re applying for a 95% or 100% mortgage.
The journey to your first home is one of the most exciting you’ll ever take. At EHF Mortgages, our job is to provide expert guidance to make it a smooth and successful one. For advice tailored to your personal situation in Chelmsford, Braintree, or Colchester, get in touch with our friendly team.





