
Top 7 Best Mortgage Lenders for First-Time Buyers UK in 2026
Securing your first mortgage can feel like a monumental task, but with the right guidance, it is an achievable and exciting step towards homeownership.
💡 Top Tip: Do not just focus on the lowest interest rate; the lender’s criteria, fees, and flexibility for first-time buyers are just as crucial.
We will explain more later in the article.
This article is designed to cut through the noise and provide a clear, actionable comparison of the best mortgage lenders for first-time buyers in the UK. We understand that whether you are in Essex or elsewhere in the country, you need straightforward information to make a confident decision. Forget wading through endless jargon-filled websites. We have organised everything you need into one place.
Inside, you will find a detailed breakdown of top lenders like Nationwide, Halifax, and Santander, complete with screenshots and direct links. We will cover key factors such as their typical deposit requirements, strengths for new buyers, and the types of products they specialise in. This will help you create a shortlist of lenders that align with your financial situation. As you plan your budget, it is also wise to consider future running costs; understanding topics like navigating the energy price cap can help you build a complete financial picture.
Our goal is to give you the clarity needed to move forward. This guide will help you compare your options effectively, understand common pitfalls, and see how a whole-of-market broker can unlock deals you might not find on your own.
Table of Contents
The Top 7 Mortgage Lenders for First-Time Buyers: A Detailed Review
Common Mortgage Pitfalls for First-Time Buyers (And How to Avoid Them)
How We Ranked the Best Lenders for First-Time Buyers
To determine the best mortgage lenders for first-time buyers in the UK, we evaluated each provider against a set of criteria that directly address the challenges new buyers face. Our ranking is not just about the lowest rates; it is about overall value, accessibility, and support.
First-Time Buyer Incentives: We prioritised lenders offering tangible benefits such as cashback at completion, reduced fees, or specific products designed for new buyers.
Deposit Requirements: Accessibility is key. We looked for lenders consistently offering high loan-to-value (LTV) products, including 95% mortgages and innovative low-deposit schemes.
Flexibility & Criteria: Lenders with more flexible affordability calculations, options for family support (such as guarantor or joint-borrower sole proprietor mortgages), and a willingness to consider varied income sources ranked higher.
Customer Support & Resources: The quality of guidance, online tools, and the accessibility of advisers were crucial. A smooth, supportive journey from application to completion is invaluable for first-time buyers.
Market Access (for Brokers): For whole-of-market brokers like EHF Mortgages, the key metric is the breadth of their lender panel, including access to specialist and intermediary-only deals that are not available directly to the public.
The Top 7 Mortgage Lenders for First-Time Buyers: A Detailed Review
Below is our detailed review of the leading options for first-time buyers in the UK. We have broken down the key features of each lender to help you compare them side-by-side.
1. EHF Mortgages (Whole-of-Market Broker)
For first-time buyers, the sheer volume of mortgage products and lender requirements can feel overwhelming. This is where a whole-of-market mortgage broker like EHF Mortgages demonstrates its true value. Rather than representing a single bank or building society, EHF provides access to a vast network of lenders, including high-street giants and specialist providers. This approach significantly increases the chances of finding not just any deal. Still, the right deal for your specific financial situation, making them a standout choice for anyone looking for the best mortgage lenders for first-time buyers in the UK.
With over 35 years of industry experience, the team at EHF Mortgages brings a depth of knowledge that is particularly beneficial for those new to the property market. They have a proven track record, having facilitated over £500 million in mortgage completions since 2017. Their expertise extends beyond straightforward applications; they are adept at handling complex cases that mainstream lenders. might reject. This includes securing finance for the self-employed, applicants with adverse credit histories, or those purchasing non-standard properties.
Key Strengths and Features
EHF Mortgages distinguishes itself through a combination of market access, expert advice, and a client-first service model.
Whole-of-Market and Specialist Access: Their ability to search deals from a wide array of lenders is their core strength. This means you are not limited to the products of just one institution. If you have a low deposit, are newly self-employed, or have a blip on your credit file, EHF can identify niche lenders with more flexible criteria.
Integrated Protection Advice: Buying a home is the biggest financial commitment most people will ever make. EHF provides advice on life insurance, critical illness cover, and income protection in addition to your mortgage. This ensures your home and family are protected from unforeseen events, offering peace of mind under one roof.
Client-Focused Process: The journey starts with a free, no-obligation 30-minute consultation to assess your needs. A key advantage is their fee structure: fees are typically only charged once a formal mortgage offer has been secured, so there are no upfront advice costs.
Proven Credibility: As a directly authorised firm by the Financial Conduct Authority (FCA No. 940123), EHF Mortgages operates to the highest regulatory standards, ensuring the advice you receive is professional and accountable.
For those just starting their property search in areas like Chelmsford or Braintree, it is worth exploring the resources available. You can learn more about their tailored first-time buyer mortgage services to understand how they can guide you through each step of the process.
“Working with a whole-of-market broker is like having a key to every lender’s door. We can find specialist deals that are not available on the high street, which is often the difference between getting a mortgage or being declined, especially for first-time buyers with unique circumstances.”
| Feature | What It Means for First-Time Buyers |
|---|---|
| Whole-of-Market Access | More choice and a higher chance of being accepted for a competitive rate. |
| Specialist Lender Panel | Solutions for complex situations (e.g., self-employed, minor credit issues). |
| Integrated Protection | A complete financial safety net for your new home and mortgage. |
| No Upfront Advice Fees | You only pay for the advice once a mortgage offer is successfully issued. |
| FCA Authorisation | Regulated, professional advice you can trust. |
Website: https://www.ehfmortgages.co.uk
2. Nationwide Building Society
As the UK’s largest building society, Nationwide has a well-earned reputation for prioritising first-time buyers. Its member-owned structure often translates into competitive products and buyer-focused incentives, making it a strong contender for anyone stepping onto the property ladder. Their website provides a clear journey, from initial affordability checks to full mortgage applications, with dedicated sections explaining the support available.
Nationwide stands out with several distinct features designed to give new buyers a boost. This commitment makes them one of the best mortgage lenders for first-time buyers in the UK, especially for those who need a little extra help with affordability or upfront costs.
Key Features for First-Time Buyers
Nationwide’s offerings are specifically structured to address common first-time buyer challenges, such as stretching affordability and managing initial expenses.
Helping Hand Policy: This scheme is a significant advantage, potentially allowing eligible first-time buyers to borrow more than standard affordability calculations would permit. It can increase the loan-to-income (LTI) multiple, opening up more property options, particularly in higher-priced areas like those across Essex.
£500 Cashback: A popular and long-standing offer, this cashback is paid to first-time buyers upon completion of their mortgage. This can be a welcome contribution towards legal fees, moving costs, or even a new piece of furniture.
Green Reward: For buyers purchasing an energy-efficient home (typically with a high EPC rating), Nationwide has offered cashback incentives. This aligns with the growing desire for sustainable living and can help offset the costs of a greener property.
95% LTV Mortgages: Nationwide consistently offers products for buyers with just a 5% deposit. While it is always beneficial to have a larger deposit, these high-LTV options are essential for those who find it challenging to save a substantial sum.
While Nationwide offers a robust digital platform, its large branch network provides valuable in-person support for those who prefer face-to-face advice. However, it is important to remember that offers like cashback and the Helping Hand scheme have specific eligibility criteria and can be withdrawn. A whole-of-market broker can verify your eligibility for these specific schemes and compare them against deals from other lenders that might be more suitable.


3. Halifax
As one of the UK’s most recognisable high-street banks, Halifax, part of Lloyds Banking Group, has a long history of supporting first-time buyers. Their proposition is built on accessible products and helpful resources, making them a reliable starting point for anyone new to the property market. The Halifax website provides a dedicated first-time buyer hub, packed with calculators, guides, and clear steps to getting an Agreement in Principle.
Halifax stands out by offering a blend of traditional high-LTV lending with more innovative family-assisted options. This combination positions them as one of the best mortgage lenders for first-time buyers in the UK, catering to those saving independently and those receiving family support to get on the ladder.
Key Features for First-Time Buyers
Halifax’s product suite is designed to address the primary hurdles for new buyers: saving a deposit and meeting affordability criteria.
Family Boost Mortgage: This standout feature is for buyers with family help. A family member deposits savings into a special Halifax account that serves as security for the mortgage. This can enable the first-time buyer to secure a mortgage with a much smaller deposit, or even no deposit at all. The helper’s funds are returned with interest, provided mortgage payments are kept up to date.
95% LTV Mortgages: Halifax regularly offers mortgages for buyers with just a 5% deposit. These are crucial for buyers in areas like Colchester, where property prices can make saving a larger sum a significant challenge. By providing these products outside of government schemes, they offer consistent access for eligible borrowers.
Greener Home Cashback: To encourage energy efficiency, Halifax offers a cashback incentive for purchasing a property with a high Energy Performance Certificate (EPC) rating. This is a welcome bonus towards moving costs.
Extensive Guidance & Resources: The Halifax website is a rich source of information, offering detailed guides, calculators, and tools to get an Agreement in Principle online. This support is invaluable for demystifying the journey for new buyers.
While the Family Boost is an excellent option, it is important to understand the conditions. The helper’s savings are locked away and cannot be accessed during that time. Furthermore, all cashback offers and high-LTV products are subject to specific criteria. A whole-of-market broker can compare these schemes against the entire market to ensure you find the most beneficial deal.
4. NatWest
As one of the UK’s major high-street banks, NatWest provides a familiar and accessible route to homeownership for many first-time buyers. Their strength lies in combining a robust online platform, featuring clear tools and calculators, with the reassurance of in-person adviser support. The bank frequently targets the first-time buyer market with specific product incentives, making it a reliable option.
NatWest’s approach is particularly well-suited for buyers who value a blend of digital convenience and traditional banking support. Their dedicated first-time buyer hub guides users from an initial Agreement in Principle through to application, demystifying a complex process. This balance makes them one of the best mortgage lenders for first-time buyers in the UK, especially for those who want clear, upfront incentives.
Key Features for First-Time Buyers
NatWest’s offerings are designed to provide tangible financial benefits at the point of purchase, addressing the immediate cost pressures that new buyers face.
First-Time Buyer Exclusive Cashback: NatWest often runs promotions offering cashback on specific mortgage products for new buyers. This can range from a few hundred pounds to over £1,000, paid upon completion, which helps with budgeting for legal fees.
95% LTV Mortgages: The bank is a consistent provider of mortgages for buyers with a 5% deposit. These products are crucial for accessing the property market, particularly for those in areas with high property values, such as Chelmsford, where saving a larger deposit can be a significant hurdle.
Clear Online Tools: Their website offers a straightforward journey to get a Mortgage in Principle (MIP). The platform clearly outlines the information you need and provides a quick decision, which is vital for making a credible offer on a property.
Family Assistance Support: Through its adviser network, NatWest can explore options involving family support, such as guarantor mortgages. This provides an alternative pathway for those whose own income or deposit does not quite meet standard lending criteria.
While NatWest’s online tools are user-friendly, it is important to note that their best deals, including cashback offers, are not available on all mortgages and can be withdrawn. The maximum loan amount will always depend on a full affordability assessment. A broker can quickly determine if you qualify for NatWest’s deals and compare their overall value against the entire market.
5. Santander UK
Santander has made significant strides in capturing first-time buyers’ attention, tackling the biggest hurdle: the deposit. With targeted products and recent rate adjustments, this high-street giant has firmly positioned itself as a key lender for those struggling to save a large lump sum. Their website offers a dedicated first-time buyer hub that guides users through the process with clear information and affordability tools.
Santander’s main appeal lies in its aggressive approach to high loan-to-value (LTV) lending. This focus makes them one of the best mortgage lenders for first-time buyers in the UK, particularly for those with a reliable income but who find saving for a 5% or 10% deposit a near-impossible task.
Key Features for First-Time Buyers
Santander’s product design directly addresses the financial squeeze many new buyers feel, especially as the rising cost of living reduces savings potential.
Launch of Very High LTV Products: The bank has a reputation for launching headline-grabbing products, such as the previously announced 98% LTV mortgage. This type of product, which could be an option in 2026, allows buyers to proceed with a tiny deposit, dramatically shortening the time needed to save before buying a home in areas like Braintree or Colchester.
Launch Incentives: To make deals more attractive, high-LTV products are often launched with zero product fees and cashback. These perks help reduce the significant upfront costs associated with a property purchase.
Competitive Higher-LTV Rates: Beyond special launches, Santander actively competes on rates across its 85% to 95% LTV mortgage ranges. This makes their standard first-time buyer products more affordable.
Dedicated Online Hub: The bank provides a clear and supportive online journey for new buyers, with calculators, guides, and checklists to help them prepare for their application and understand the home-buying process.
While a very low deposit mortgage is an incredible opportunity, it is vital to understand the implications. Such products come with strict eligibility criteria and may have been subject to restrictions (e.g., new builds are often excluded). Borrowing such a high percentage also means you have very little equity, making you more vulnerable to negative equity. A whole-of-market mortgage broker can navigate these complexities and confirm if you and your chosen property meet the lender’s strict criteria.
6. Skipton Building Society
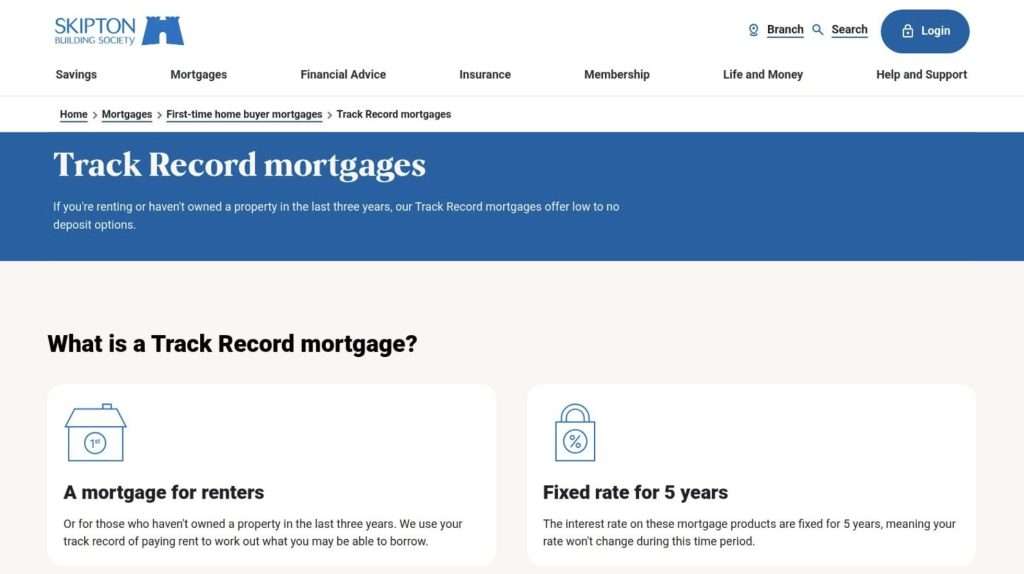
As a mutual building society, Skipton has gained significant attention for its direct approach to tackling one of the biggest hurdles for first-time buyers: the deposit. Its innovative product for renters makes it a standout choice, especially for those with a strong payment history but limited savings. The website offers a clear, user-friendly experience with modern tools and soft-search Decisions in Principle, allowing buyers to check their standing without impacting their credit score.
Skipton’s commitment to finding practical solutions solidifies its position as one of the UK’s best mortgage lenders for first-time buyers. Their headline-grabbing mortgage product is particularly relevant for renters in areas with high rental costs, like Colchester, where saving a deposit while paying rent can feel impossible.
Key Features for First-Time Buyers
Skipton’s offerings are centred around providing a genuine pathway to homeownership for those struggling with the initial financial barriers.
Track Record Mortgage: This is a genuine 100% LTV (no-deposit) mortgage aimed at renters. To be eligible, applicants must demonstrate a consistent 12-month history of paying rent and household bills. It is a five-year fixed-rate product, providing payment security for the crucial first years of homeownership.
No Completion Fee on Track Record: A significant benefit of the Track Record mortgage is the absence of a completion fee. This helps dramatically reduce the upfront costs of buying a home.
95% LTV Mortgages: Beyond its no-deposit option, Skipton also offers a standard range of mortgages for buyers with a 5% deposit, ensuring it caters to a broader spectrum of first-time buyers.
Delayed Start Option: On selected products, Skipton offers the flexibility to delay the first mortgage payment for up to three months. This can be a lifesaver, providing breathing room to cover other moving-related costs.
While the Track Record mortgage is a fantastic innovation, it comes with strict eligibility criteria. Applicants must have a clean credit history and provide evidence of their rental payments. The five-year fixed term also comes with early repayment charges (ERCs). A broker can help you navigate this scheme’s specific requirements and confirm whether it is the right fit for your situation.
7. Yorkshire Building Society (YBS)
As another of the UK’s major mutuals, Yorkshire Building Society (YBS) has built a strong reputation for developing practical solutions aimed directly at first-time buyers. Their member-first ethos shines through in products that tackle the core challenges of getting onto the property ladder: saving a deposit and managing upfront costs. The YBS website is straightforward, offering clear information on their mortgage range and dedicated support for new buyers.
YBS stands out for its bold, innovative schemes that directly address the deposit hurdle. This focused support makes them one of the best mortgage lenders for first-time buyers in the UK, particularly for those who can get a foot on the ladder with just a small amount of capital saved.
Key Features for First-Time Buyers
Yorkshire Building Society’s offerings are designed to provide tangible financial assistance, helping many aspiring buyers make homeownership a reality sooner.
£5k Deposit Mortgage: This standout product allows eligible first-time buyers to purchase a property with just a £5,000 deposit, on properties valued up to £500,000. This is a game-changer for those finding it difficult to save the traditional 5% or 10%, especially in areas with higher property prices like Colchester.
Promotional Cashback Offers: YBS is known for running attractive cashback promotions on selected first-time buyer mortgages. These can provide a significant lump sum upon completion, covering legal fees or moving expenses.
Fee-Assisted Products: Many of their first-time buyer mortgages include incentives such as a free standard valuation or a no product fee, helping lower the initial cost of securing a mortgage.
Advised Product Options: Recognising that the mortgage process can be complex, YBS offers products available through mortgage advisers. This ensures buyers receive expert guidance to secure the right deal for their situation.
While the £5k deposit scheme is a headline grabber, it is vital to understand the strict eligibility criteria and that these innovative products are often time-limited. Some of the most attractive deals are only accessible via an adviser. A whole-of-market broker can confirm if you qualify for these specific YBS products and weigh them against the entire market to ensure you are not missing out on a potentially better rate or more suitable deal elsewhere.
Top 7 UK Mortgage Lenders for First-Time Buyers: Comparison Table
| Provider | Key Advantage | Best For | Deposit Needed | Available Via |
|---|---|---|---|---|
| EHF Mortgages | Whole-of-market access and specialist deals | Complex cases or finding the best overall deal | From 0% | Broker Only |
| Nationwide | ‘Helping Hand’ affordability boost | Borrowers needing to maximise their loan size | From 5% | Direct & Broker |
| Halifax | ‘Family Boost’ mortgage using family savings | Buyers with family help for the deposit | From 0% | Direct & Broker |
| NatWest | Clear and consistent cashback offers | Buyers wanting a simple financial perk | From 5% | Direct & Broker |
| Santander | Potential for very low deposit products (e.g. 2%) | Buyers with minimal savings but good income | From 2-5% | Direct & Broker |
| Skipton BS | ‘Track Record’ mortgage for renters | Renters with a strong payment history | From 0% | Direct & Broker |
| Yorkshire BS | Innovative £5k fixed deposit scheme | Buyers who can save £5,000 but not 5% | £5,000 fixed | Broker Only |
First-Time Buyer Checklist: Are You Mortgage Ready?
Before you apply, make sure your finances are in order. Use this checklist to see if you are prepared:
Check Your Credit Score: Obtain your reports from Experian, Equifax, and TransUnion. Check for errors and see where you can improve.
Gather Your Documents: You will need at least 3 months of payslips and bank statements, ID (passport/driving licence), and proof of your deposit.
Minimise Your Debts: Pay down credit cards, personal loans, and overdrafts where possible. Lenders scrutinise your debt-to-income ratio.
Create a Budget: Understand exactly what you spend each month. This will help you determine a realistic mortgage payment and show lenders you are financially responsible.
Get an Agreement in Principle (AIP): An AIP shows sellers you are a serious buyer. You can get one from a lender or a broker.
Common Mortgage Pitfalls for First-Time Buyers (And How to Avoid Them)
The path to homeownership has a few common tripwires. Being aware of them is the best way to ensure a smooth journey.
Ignoring Additional Costs: The deposit is not the only expense. Budget for solicitor fees, valuation fees, stamp duty, and moving costs.
Applying for Too Much Credit: Avoid taking out new car loans, phone contracts, or credit cards in the months before your application. Every credit search can impact your score.
Fixating on the Interest Rate: As we mentioned at the start, the lowest rate is not always the best deal. A mortgage with a slightly higher rate but no arrangement fee might be cheaper overall. A broker can do these calculations for you.
Going Direct to Your Bank: Your own bank will only offer you its own products. You could be missing out on a much better deal from another lender. A whole-of-market broker compares dozens of lenders to find the right fit.
Ready to Take the Next Step?
Navigating the complexities of the mortgage market alone can be daunting. At EHF Mortgages, we specialise in helping first-time buyers in Essex and across the UK find the perfect mortgage for their needs. By comparing products from across the entire market, we ensure you secure the most suitable and competitive deal, taking the stress out of the process so you can focus on finding your dream home.
Choosing the right mortgage is the most important financial decision you will make when buying your first home. An experienced broker can match your unique financial situation to the lender most likely to say ‘yes’, saving you time, stress, and potentially thousands of pounds. We offer a free, no-obligation initial consultation to assess your situation and outline your options. Let us handle the complexity, so you can focus on the excitement of finding your perfect first home.





