
💡 Top Tip: Don’t just assume your standard life insurance policy will do the job. The best mortgage protection insurance is actually a clever mix of different policies designed to shield you from death, serious illness, AND losing your job.
We’ll get into the nuts and bolts of building this financial safety net later on.
Building a Financial Safety Net for Your Home
Getting the keys to your new home is a massive achievement. It’s more than just bricks and mortar; it’s the foundation for your future. But what happens if that foundation is shaken?
The term ‘mortgage protection insurance’ can be a bit confusing. It’s not a single, off-the-shelf product you can add to your basket. It’s better to think of it as a personalised financial toolkit, built specifically to keep your home safe if life throws a curveball.
This guide cuts through the jargon and explains exactly how to protect your home against life’s biggest uncertainties. We believe the best mortgage protection isn’t one policy, but a strategic combination of cover. Whether you’re a first-time buyer in Chelmsford or a family in Braintree looking over your finances, getting your head around this is a cornerstone of responsible homeownership.
What This Guide Covers
We’re going to walk you through everything, from the basic building blocks of cover to crafting a plan that fits your life like a glove. Of course, building a solid financial foundation also means being prepared for big moments, such as mortgage approval.
Here’s a look at what’s coming up:
- Understanding the Core Types of Mortgage Protection
- How Much Does Mortgage Protection Insurance Cost
- Finding the Best Cover for Your Unique Situation
- Common Exclusions and Policy Details to Watch For
- Frequently Asked Questions About Mortgage Protection
- How We Can Help Secure Your Financial Future
Our goal is simple: to give you the knowledge to make smart, confident decisions. Getting your mortgage is the first big step; protecting it is what guarantees long-term security for you and your loved ones. This is about more than just insurance; it’s about creating a robust defence for your most important asset.
Understanding the Core Types of Mortgage Protection
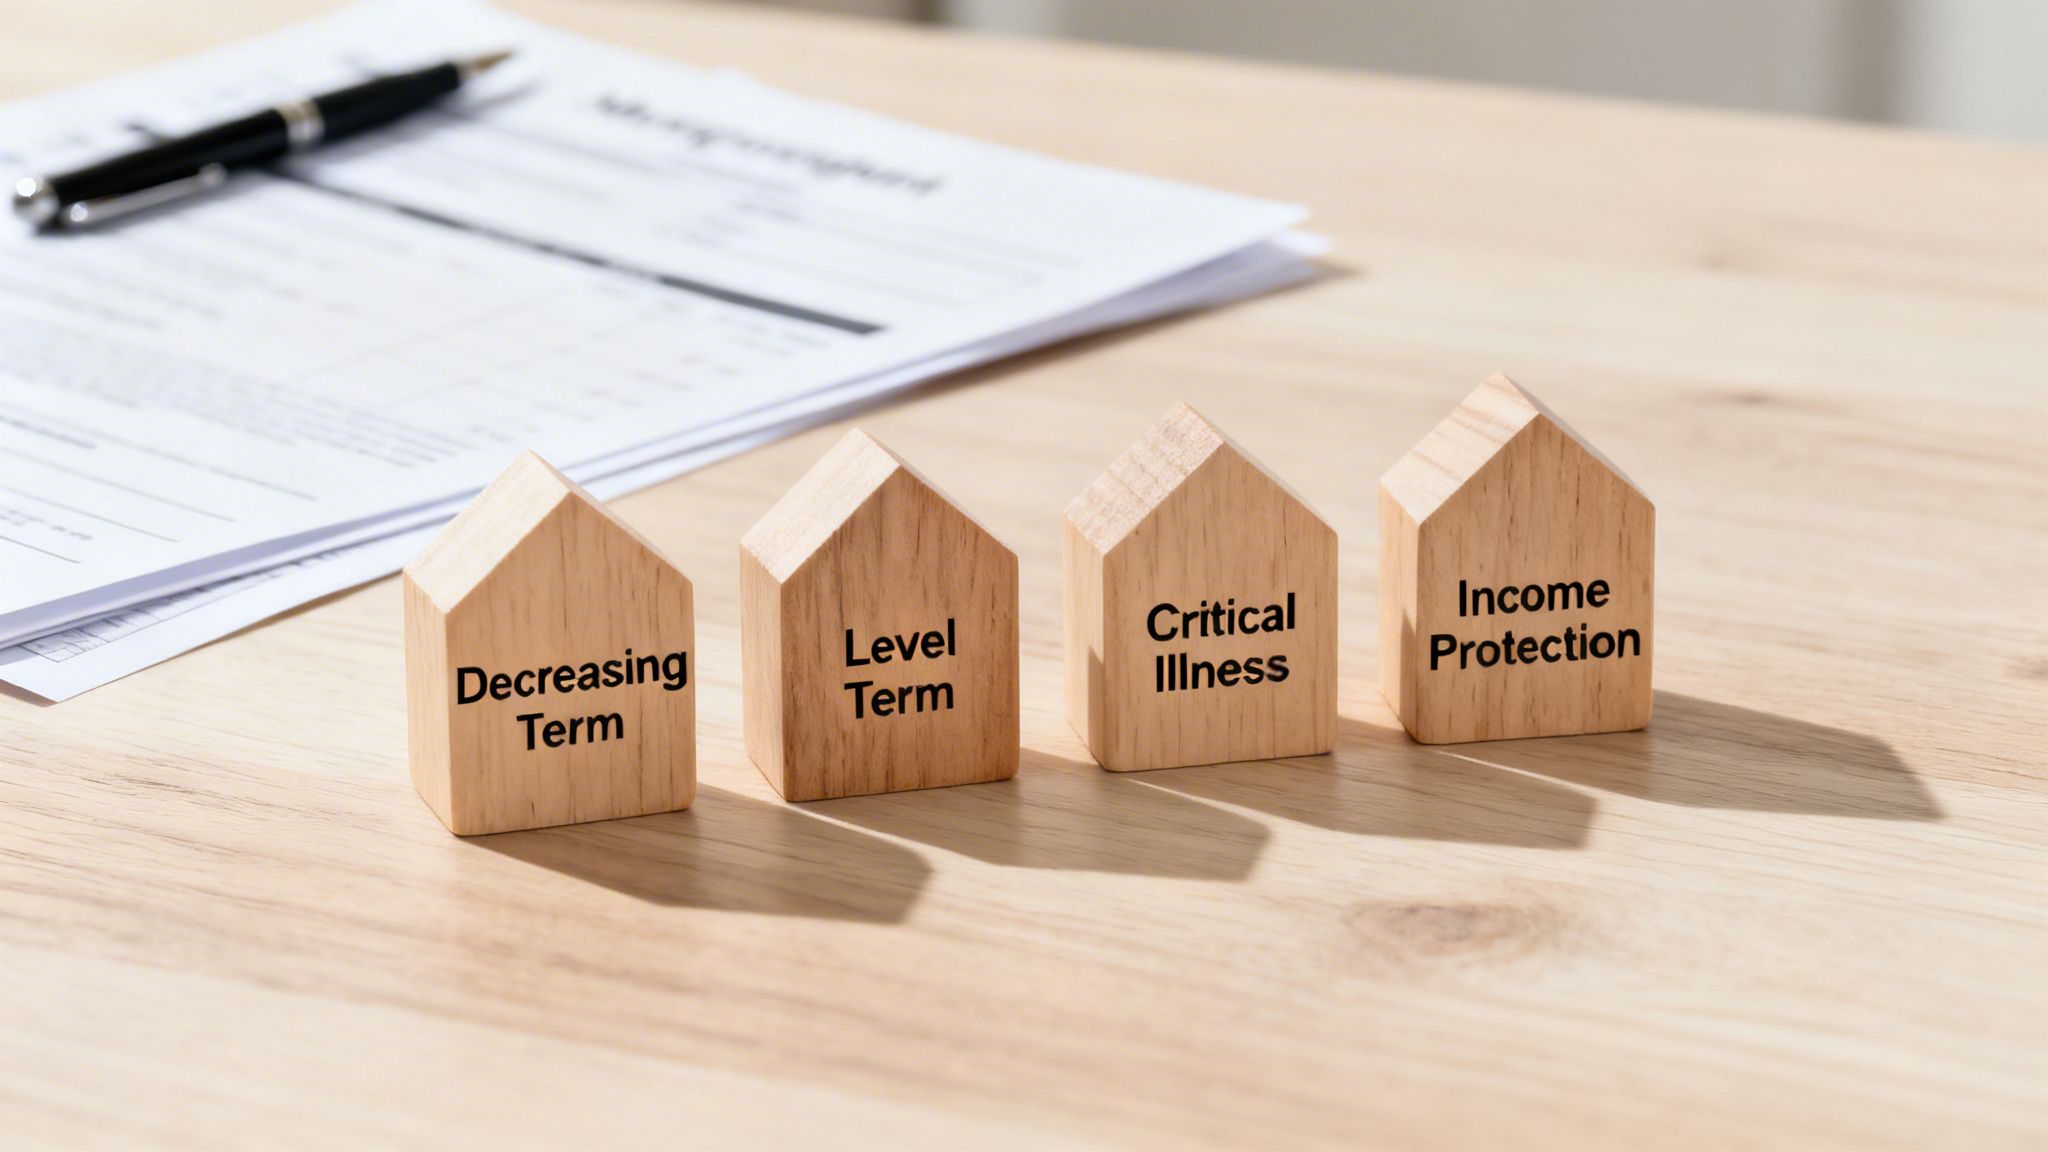
When you start looking for the “best mortgage protection insurance,” you’ll quickly realise it isn’t a single, off-the-shelf product. It’s more like building a personalised defence system for your finances, using several core types of cover. Each one is designed to shield you and your family from a different kind of financial shock.
Think of it like building a house. You need strong foundations, sturdy walls, and a solid roof. Each part does a very different but equally important job. Let’s break down these key components so you can see how they fit together to safeguard your home.
Life Insurance: The Foundation of Your Plan
Life insurance is the bedrock of almost any mortgage protection strategy. Put simply, it’s designed to pay out a lump sum if you pass away during the policy term. This gives your loved ones the means to repay the mortgage and stay in the family home.
There are two main variations you’ll come across:
Decreasing Term Life Insurance: Imagine a shield that shrinks in perfect sync with your mortgage balance. As you pay down your loan over the years, the potential payout from the policy also reduces. This direct link makes it a very cost-effective way to cover a standard repayment mortgage.
Level Term Life Insurance: This cover is more like a consistent safety net. The payout amount stays the same throughout the entire policy term, no matter how much you owe on your mortgage. This makes it a great fit for interest-only mortgages or for families who want to leave a fixed sum after clearing the debt.
It’s also worth noting that understanding how life insurance proceeds and probate interact is vital to ensuring the payout reaches your family smoothly.
Critical Illness Cover: Your Financial First-Aid Kit
What if you don’t pass away, but become too ill to work? A serious diagnosis like cancer, a heart attack, or a stroke can have a devastating financial impact, right when you need to focus on your health. This is where Critical Illness Cover steps in.
This policy is your financial first-aid kit. It pays out a tax-free lump sum if you are diagnosed with one of the serious conditions listed in your policy documents. This money can be used to pay off the mortgage entirely, giving you the financial breathing room to recover without the stress of losing your home.
We explain this in much more detail in our article exploring whether you need critical illness cover for a mortgage.
Income Protection: Your Financial Stand-In
Finally, let’s think about what happens if an illness or injury stops you from earning, but it isn’t classed as ‘critical’. Something like a serious back problem or mental health issues could keep you out of work for months, or even years. This is precisely the risk that Income Protection is designed to manage.
Think of it as your financial stand-in. If a doctor signs you off work, the policy pays you a regular, tax-free monthly income after a pre-agreed waiting period. This ensures you can keep up with your mortgage payments and other essential bills while you focus on getting better.
A hidden crisis looms for over 1 in 4 UK homeowners, who risk losing their property because of an unprotected health emergency. This ‘protection gap’ is a serious threat, yet awareness is worryingly low: only 15% of mortgage holders fully understand what income protection actually does.
Quick Comparison of Mortgage Protection Policies
To help you see how these policies stack up against each other, here’s a quick side-by-side comparison. It’s a simple way to understand their key features at a glance.
| Policy Type | What It Covers | Payout Type | Best For |
|---|---|---|---|
| Decreasing Term | Death during the term | Lump sum that reduces over time | Repayment mortgages |
| Level Term | Death during the term | Fixed lump sum | Interest-only mortgages, inheritance planning |
| Critical Illness | Diagnosis of a specified serious illness | Tax-free lump sum | Clearing debt & covering costs during recovery |
| Income Protection | Inability to work due to illness/injury | Regular monthly income | Replacing lost earnings for all bills |
Getting to grips with these distinct policy types is the first, most important step towards building the right mortgage protection strategy for you and your family.
How Much Does Mortgage Protection Insurance Cost
Let’s get straight to the big question: what’s this all going to cost? It’s a common assumption that putting a proper safety net in place for your mortgage will come with a hefty price tag. But in reality, comprehensive cover is often far more affordable than most people imagine.
Finding the right mortgage protection isn’t about hunting for the cheapest premium you can find online. It’s about getting the best value for your specific situation. The cost isn’t just a number plucked from thin air; insurers calculate it carefully based on personal and policy-related factors that paint a picture of their risk. Once you understand what these are, the pricing makes a lot more sense.
Key Factors That Influence Your Premiums
Insurers are essentially trying to work out the likelihood of having to pay a claim. The higher they perceive that risk to be, the higher your monthly premium will be.
Here are the main things they’ll look at when you apply:
- Your Age: It’s a simple fact of life that younger applicants tend to get lower premiums. Statistically, they are less likely to suffer from serious health problems, making them a lower risk.
- Your Health and Lifestyle: You’ll be asked detailed questions about your medical history and that of your close family. Lifestyle choices, especially smoking or vaping, play a huge role. Being a non-smoker in good general health will dramatically reduce your costs.
- Your Occupation: Some jobs carry more risk than others. An office worker will likely face lower premiums than a construction worker or scaffolder because of the higher risk of accidents.
- The Mortgage Amount: This one’s straightforward. The bigger the loan you need to protect, the higher the premium will be.
- The Policy Term: The length of time you need to be covered for is also key. A 30-year mortgage term will naturally cost more to insure than a shorter 15-year term.
- The Type and Level of Cover: A basic decreasing term life insurance policy is the most budget-friendly option. If you decide to add critical illness cover or a comprehensive income protection plan, the cost will increase, but so will the scope of your financial safety net.
Price vs. Value: A Real-World Example
To see how this works in practice, let’s imagine two different homeowners in Essex.
First, we have a 28-year-old first-time buyer in Braintree. They’re a non-smoker in good health with a £200,000 repayment mortgage over 30 years. For them, a basic decreasing term life insurance policy could cost very little each month, perhaps less than a couple of takeaway coffees.
Now, consider a 45-year-old homeowner in Colchester with a £400,000 mortgage. They are smokers and want a more robust plan that includes critical illness cover. Their premium will be significantly higher, reflecting their age, lifestyle, the larger loan, and the much broader level of protection they’ve chosen.
Average Cost Examples for a Non-Smoker
To give you a clearer idea, here are some illustrative monthly costs for a healthy, non-smoking individual looking for £250,000 of cover over a 25-year term.
| Age | Decreasing Term Life Only | Level Term Life Only | Decreasing Term + Critical Illness |
|---|---|---|---|
| 30 | £8-£12 | £12-£16 | £35-£50 |
| 40 | £14-£20 | £22-£30 | £65-£85 |
| 50 | £35-£50 | £60-£80 | £150-£200 |
Please note: These figures are for illustrative purposes only, and the actual premium you pay will depend on your individual circumstances and a full underwriting assessment.
Ultimately, the goal is to strike the right balance between a premium that fits your budget and a level of protection that truly safeguards your home. An independent adviser is invaluable here, helping you navigate the options to ensure you aren’t paying for cover you don’t need, while making absolutely certain your family is never left vulnerable.
Finding the Best Cover for Your Unique Situation
Let’s be clear: there is no single “best” mortgage protection insurance policy out there. The right cover for a first-time buyer in their twenties will look completely different to the ideal plan for a self-employed business owner or someone borrowing later in life. It all comes down to your personal circumstances.
So, instead of hunting for a generic solution, the real goal is to find the best cover for your unique situation. Let’s walk through how different life stages and professions shape what kind of protection makes the most sense.
Guidance for First-Time Buyers
When you’re a first-time buyer, you’re often stretching your finances to the absolute limit. Budgets are tight, I get it. But this is precisely when putting protection in place is most critical. With a huge new debt and maybe not much in savings, even a short-term loss of income could cause serious headaches.
The key is to focus on securing affordable, essential cover right from day one.
- Core Priority: A decreasing term life insurance policy is usually the most cost-effective place to start. It’s designed to clear the mortgage balance if the worst were to happen, ensuring your partner or family isn’t left struggling with the debt.
- Consider Adding: If your budget can stretch a little further, adding critical illness cover provides another crucial layer of security. A serious illness can be just as financially devastating as a death in the family.
For most young buyers, the peace of mind this foundational cover brings is invaluable. It’s about building a safety net right at the start of your homeownership journey.
Advice for Remortgagers and Home Movers
If you’re moving home or remortgaging, perhaps in areas like Chelmsford or Colchester, it’s the perfect time to give your protection policies a proper review. Life has probably changed a fair bit since you first took out your mortgage. You might have a bigger loan, a growing family, or a higher salary to protect.
A common mistake is to let an old policy roll over simply. An outdated plan can leave a dangerous gap between what you now owe and what the policy would actually pay out. This situation also occurs when you change the amount you are borrowing or adjust the mortgage term.
Your personal circumstances, the mortgage details, and the type of cover you choose all come together to determine your policy’s cost and whether it’s right for you.
Essential Cover for the Self-Employed
For anyone self-employed, the need for robust protection is even more pressing. You don’t have the safety net of company sick pay, paid holidays, or death-in-service benefits. If you can’t work, your income stops. Dead. This makes Income Protection an absolutely non-negotiable part of your financial planning.
It’s a sobering thought, but in the UK, a staggering 2.3 million mortgage holders have no financial safety net at all. That’s 36% of all UK mortgage holders completely exposed if the main earner falls ill or passes away. You can discover more insights from the 2025 HomeOwner Survey by Lifesearch.
For an in-depth look at this vital cover, you can learn more about income protection insurance in our detailed guide. Think of it as your own personal sick pay scheme. It provides a monthly income to cover your mortgage and bills if you’re unable to work due to illness or injury.
Protecting Your Mortgage in Later Life
Borrowing later in life, maybe with a Retirement Interest-Only (RIO) mortgage, brings a different set of protection needs to the table. The main goal here is often tensurere the mortgage is paid off at your death without forcing the sale of the family home, preserving it as an inheritance for your loved ones.
In this scenario, level term life insurance is often the most suitable choice. Unlike a decreasing policy, the payout amount stays the same throughout the term. This makes it perfect for covering an interest-only mortgage, where the capital balance doesn’t decrease. It guarantees that a specific lump sum will be there to settle the loan, providing complete certainty for your beneficiaries.
Common Exclusions and Policy Details to Watch For
Choosing the right mortgage protection isn’t just about picking the right types of cover; it’s about getting to grips with the small print. A policy is a contract, after all, and knowing what is and isn’t covered is essential if you want it to come through for you when you need it most. This is where many people trip up, making assumptions that can lead to a claim being denied later.
Think of it like checking the specs before buying a car. You wouldn’t just look at the colour; you’d want to know about the engine, safety features, and running costs. Digging into the policy details is just as important, as it helps you avoid common pitfalls and make a truly informed decision, giving you genuine peace of mind.
Understanding Common Policy Exclusions
Every insurance policy has exclusions, specific circumstances or events that aren’t covered. Being aware of these from the outset is crucial.
Common exclusions often include:
- Non-Disclosure: This is the big one. Failing to disclose a pre-existing medical condition, a risky job, or lifestyle choices like smoking during your application can invalidate your policy. Absolute honesty is non-negotiable here.
- Self-Inflicted Injuries: Most policies will not pay out for claims arising from intentionally self-inflicted injuries or suicide, especially within the first 12 months of the policy.
- High-Risk Activities: If you take part in hazardous sports or hobbies (like skydiving or rock climbing) and haven’t declared them, any related claim could be rejected.
- Alcohol or Drug Misuse: Claims related to illness or injury caused by excessive alcohol consumption or illegal drug use are typically excluded.
The demand for good-quality mortgage protection is growing fast across the UK. Adviser surveys show significant growth and optimism for 2025 and beyond, with 95% of mortgage advisers reporting a sharp increase in protection sales. This trend is expected to continue as many borrowers come off fixed-rate deals, freeing up income to secure their financial safety nets. Read the full report on rising protection sales.
Guaranteed vs Reviewable Premiums
When you get a quote, you’ll see one of two premium types: guaranteed or reviewable. Understanding the difference is vital for your long-term financial planning.
| Premium Type | How It Works | Long-Term Cost | Best For |
|---|---|---|---|
| Guaranteed | The monthly premium is fixed for the entire policy term. It will not change. | Predictable and often cheaper over the full term. | Budgeting and long-term financial certainty. |
| Reviewable | The insurer can review and increase your premium, usually every 5 years. | Starts cheaper but can become very expensive over time. | Those on an extremely tight initial budget. |
While a reviewable premium might look tempting with its lower starting cost, it can become unaffordable later on. A guaranteed premium gives you certainty, ensuring your protection stays affordable for the entire life of your mortgage.
The Deferment Period Explained
For income protection policies, the deferment period (also called the waiting period) is a key detail you can’t overlook. It’s the length of time you have to be off work before the policy starts paying out, which can range from one week to 12 months.
Aligning this period with your financial situation is a smart move. For example, if your employer in Braintree provides six months of full sick pay, you could set your deferment period to six months. This means you won’t be paying for cover you don’t need, which helps to lower your monthly premium.
Frequently Asked Questions About Mortgage Protection
The world of mortgage protection can feel a bit like alphabet soup, with lots of acronyms and confusing terms. To cut through the noise, we’ve put together some straightforward answers to the questions we hear most often from homeowners here in Essex and across the UK.
Is Mortgage Protection Insurance Compulsory in the UK
The short answer is no. There’s no legal requirement to have mortgage protection insurance in the UK. Your lender will insist on buildings insurance to protect their investment, but policies like life or critical illness cover are entirely your choice.
That said, any good mortgage adviser will tell you it’s a conversation you absolutely need to have. Without a safety net in place, your family could be at risk of losing their home if you died or couldn’t work. Think of it as an essential part of responsible financial planning.
What Is the Difference Between MPPI and Income Protection
This is a really important distinction, and one that trips up a lot of people. Mortgage Payment Protection Insurance (MPPI) is a very specific type of cover. It’s designed to do just one thing: cover your monthly mortgage payments if you can’t work, and usually only for a limited period of 12 to 24 months.
Income Protection (IP) is a much broader and more powerful financial backstop. It’s designed to replace a significant percentage of your salary, and the payments can continue for years, sometimes right up until retirement. You can use that money for anything, not just the mortgage, covering everything from bills and food to other daily expenses.
Can I Get Mortgage Protection with a Pre-existing Medical Condition
In most cases, yes, you absolutely can. The golden rule here is complete honesty. You must fully disclose any and all pre-existing conditions when you apply. Trying to hide something could result in a future claim being rejected, which defeats the whole purpose of having the policy.
Depending on your specific condition, the insurer might:
- Offer you cover on their standard terms with no price change.
- Increase your monthly premium to reflect the added risk.
- Add a specific exclusion related to your condition.
This is exactly where an independent broker like us proves invaluable. We have access to specialist insurers and a deep understanding of the market, so we know which providers are more accommodating for different medical histories, ensuring you get fair terms.
Should My Partner and I Get a Joint or Single Policy
There’s no single correct answer to that; it comes down to what you want to achieve and what your budget allows. A joint ‘first death’ policy is often the most cost-effective option. It pays out once the first partner dies, clearing the mortgage, and then the policy ends.
The alternative is taking out two separate single policies. This provides much more comprehensive protection. If one person dies, their policy pays out, and the surviving partner still has their own individual cover in place. It costs a little more, but it offers far greater long-term security for the remaining family.
How We Can Help Secure Your Financial Future
As we’ve explored, the ‘best’ mortgage protection insurance isn’t a one-size-fits-all product. It’s a carefully crafted strategy, built around your specific circumstances, your family’s needs, and your financial picture.
Trying to navigate this market alone, deciphering complex policy documents and comparing providers can be a real headache. That’s where we come in. With over 35 years of hands-on experience, we are independent, whole-of-market brokers dedicated to helping clients across Chelmsford, Braintree, and Colchester find the right cover at the right price.
Our job is to listen, understand what you need, and then translate that into a robust plan that covers all the angles. We handle the entire process for you, from the initial application right through to getting your policy up and running, making it straightforward and stress-free. For a deeper dive into the cornerstone of many protection plans, you can learn more about how life insurance works in our guide.
Your home is more than just bricks and mortar; it’s the heart of your family’s life. Taking the first step to protect it is simple. Let us help you put the right safeguards in place. Your home is too important to leave to chance. Contact us for a no-obligation chat to see how we can secure your financial future.





