
Want one of our top buy to let mortgage tips right now? Always plan your mortgage application around a lender’s rental income stress test not just the current interest rate. This single step prevents countless rejections and ensures your investment is profitable from day one. We’ll explain exactly how to master this and six other critical strategies in this guide.
Securing the right buy-to-let (BTL) mortgage is the foundation of a successful property investment journey. Whether you are a first-time landlord in Chelmsford or scaling a multi-property portfolio across Braintree and Colchester, the financial structure you choose will dictate your cash flow profitability and long-term growth. The market is complex, with lender criteria constantly shifting. Factors like expected rental income, local licensing requirements, and the size of your existing portfolio can dramatically affect which lenders will even consider your application. This guide provides seven actionable tips to navigate the BTL mortgage landscape with confidence, ensuring you secure the best possible terms for your investment properties in 2026 and beyond.
Table of Contents
- Understand Rental Income Requirements and Stress Testing
- Secure the Right Loan-to-Value Ratio for Better Terms
- Choose Between Interest-Only and Repayment Mortgages Strategically
- Leverage Whole-of-Market Access to Find Specialist Lenders
- Plan for Tax Efficiency and Mortgage Interest Relief
- Build a Scalable Portfolio Strategy and Structure Future Growth
- Maintain Financial Reserves and Plan for Contingencies
1. Understand Rental Income Requirements and Stress Testing
One of the most critical buy-to-let mortgage tips for any aspiring or existing landlord is to master how lenders assess affordability. Unlike residential mortgages, which focus on your personal income, a buy-to-let mortgage’s borrowing potential is primarily determined by the property’s expected rental income. Lenders need absolute confidence that the rent will comfortably cover the mortgage payments even if interest rates rise. To achieve this, they use a method called “stress testing”.
How Stress Testing Works
A stress test is a calculation lenders apply to ensure a property investment is financially viable under adverse conditions. Instead of calculating affordability based on the actual interest rate of the mortgage product, they use a higher ‘stressed’ interest rate. This is typically around 5.5% or sometimes higher, depending on the lender and the market.
Furthermore, they require the projected rental income to exceed the stressed mortgage payment by a set margin. This is known as the Interest Cover Ratio (ICR).
Standard ICR: Most lenders require an ICR between 125% and 145%.
Higher Rate Taxpayers: If you are a higher or additional rate taxpayer, lenders will often require a higher ICR, sometimes up to 165%, to account for your larger tax liability on rental income.
Example in Action:
Let’s say you want to borrow £150,000 for a property. The lender applies a stress rate of 5.5% and requires an ICR of 145%.
– Annual interest at 5.5%: £150,000 x 5.5% = £8,250
– Required annual rental income: £8,250 x 145% = £11,962.50
– Required monthly rental income: £11,962.50 / 12 = £996.88Your property must generate at least this much in monthly rent to pass the lender’s affordability check, regardless of the actual mortgage rate you secure.
Practical Steps for Success
Failing to meet these strict criteria is a common reason for application rejection. Proactive planning is therefore essential.
Get Professional Valuations: Before making an offer, consult local letting agents in areas such as Chelmsford, Braintree, and Colchester to obtain a realistic rental income valuation. This provides evidence for your application.
Target Higher Yields: Successful portfolio landlords often target properties with gross rental yields of 6-8%. This strategy builds a significant buffer, ensuring properties comfortably pass even the most stringent 145% ICR tests.
Account for Voids: When calculating your own numbers, factor in a realistic void period (typically 5-8% of the annual rent) to account for periods when the property might be empty.
Use Online Calculators: Use a buy-to-let calculator to model different scenarios. This will help you understand how changes in rent property prices or stress rates impact your maximum borrowing. For a deeper dive, you can learn more about understanding your borrowing potential.
Understanding these calculations is fundamental. Some lenders in the commercial space use a similar metric; learning about DSCR loan requirements can provide additional insight into how property income is assessed for financing.
2. Secure the Right Loan-to-Value Ratio for Better Terms
One of the most powerful yet often overlooked buy-to-let mortgage tips is strategically managing your Loan-to-Value (LTV) ratio. LTV represents the percentage of the property’s value you are borrowing. For buy-to-let investments, lenders require a significantly larger deposit than for a standard residential purchase, meaning you start with a lower LTV. This isn’t just a barrier to entry; it’s an opportunity for savvy investors to unlock superior borrowing terms.
How LTV Impacts Your Mortgage
The principle is simple: a lower LTV means a larger deposit, which reduces the lender’s risk. In return for taking on less risk, lenders reward you with more favourable terms. Buy-to-let mortgages typically require a minimum deposit of 20-25% (an 80% or 75% LTV). However, pushing this to 30% or even 40% (a 70% or 60% LTV) can make a substantial difference.
Lenders categorise their mortgage products into LTV bands. Crossing into a lower band can significantly reduce your interest rate and unlock more flexible lending criteria.
Higher LTV (e.g. 80%): You will face higher interest rates and potentially stricter affordability checks.
Lower LTV (e.g. 70%): You gain access to much more competitive interest rates, potentially larger loan amounts, and a wider choice of lenders.
Example in Action:
An investor in Chelmsford is buying a £200,000 property.
– Scenario A (75% LTV): They put down a £50,000 deposit and borrow £150,000. They might secure a rate of 4.75%.
– Scenario B (70% LTV): They put down a £60,000 deposit and borrow £140,000. By crossing this LTV threshold, they could access a 4.00% rate.The seemingly small 0.75% rate difference on the lower LTV mortgage saves them a significant amount in interest payments over the term, directly boosting their net profit.
Practical Steps for Success
Strategically managing your LTV isn’t just about finding a bigger deposit for one property. It’s about optimising the financial health of your entire portfolio.
Aim for the Sweet Spot: Target an LTV of 75% or lower from the outset. This positions you for better rates and provides a buffer against potential falls in property value.
Consider Portfolio LTV: Don’t just look at properties individually. Calculate the overall LTV across your entire portfolio. Some specialist lenders offer portfolio finance with rates based on the combined LTV allowing a high-LTV property to be balanced by a low-LTV one.
Plan for Refinancing: After several years capital growth and mortgage repayments will naturally lower your LTV. You can then refinance at a much better rate or release equity at a favourable LTV to fund your next purchase.
Use Broker Expertise: A specialist broker like EHF Mortgages has access to lenders who specifically reward lower-LTV applicants. We can compare the latest buy-to-let mortgage rates and find products that offer the biggest discounts for your deposit level.
3. Choose Between Interest-Only and Repayment Mortgages Strategically
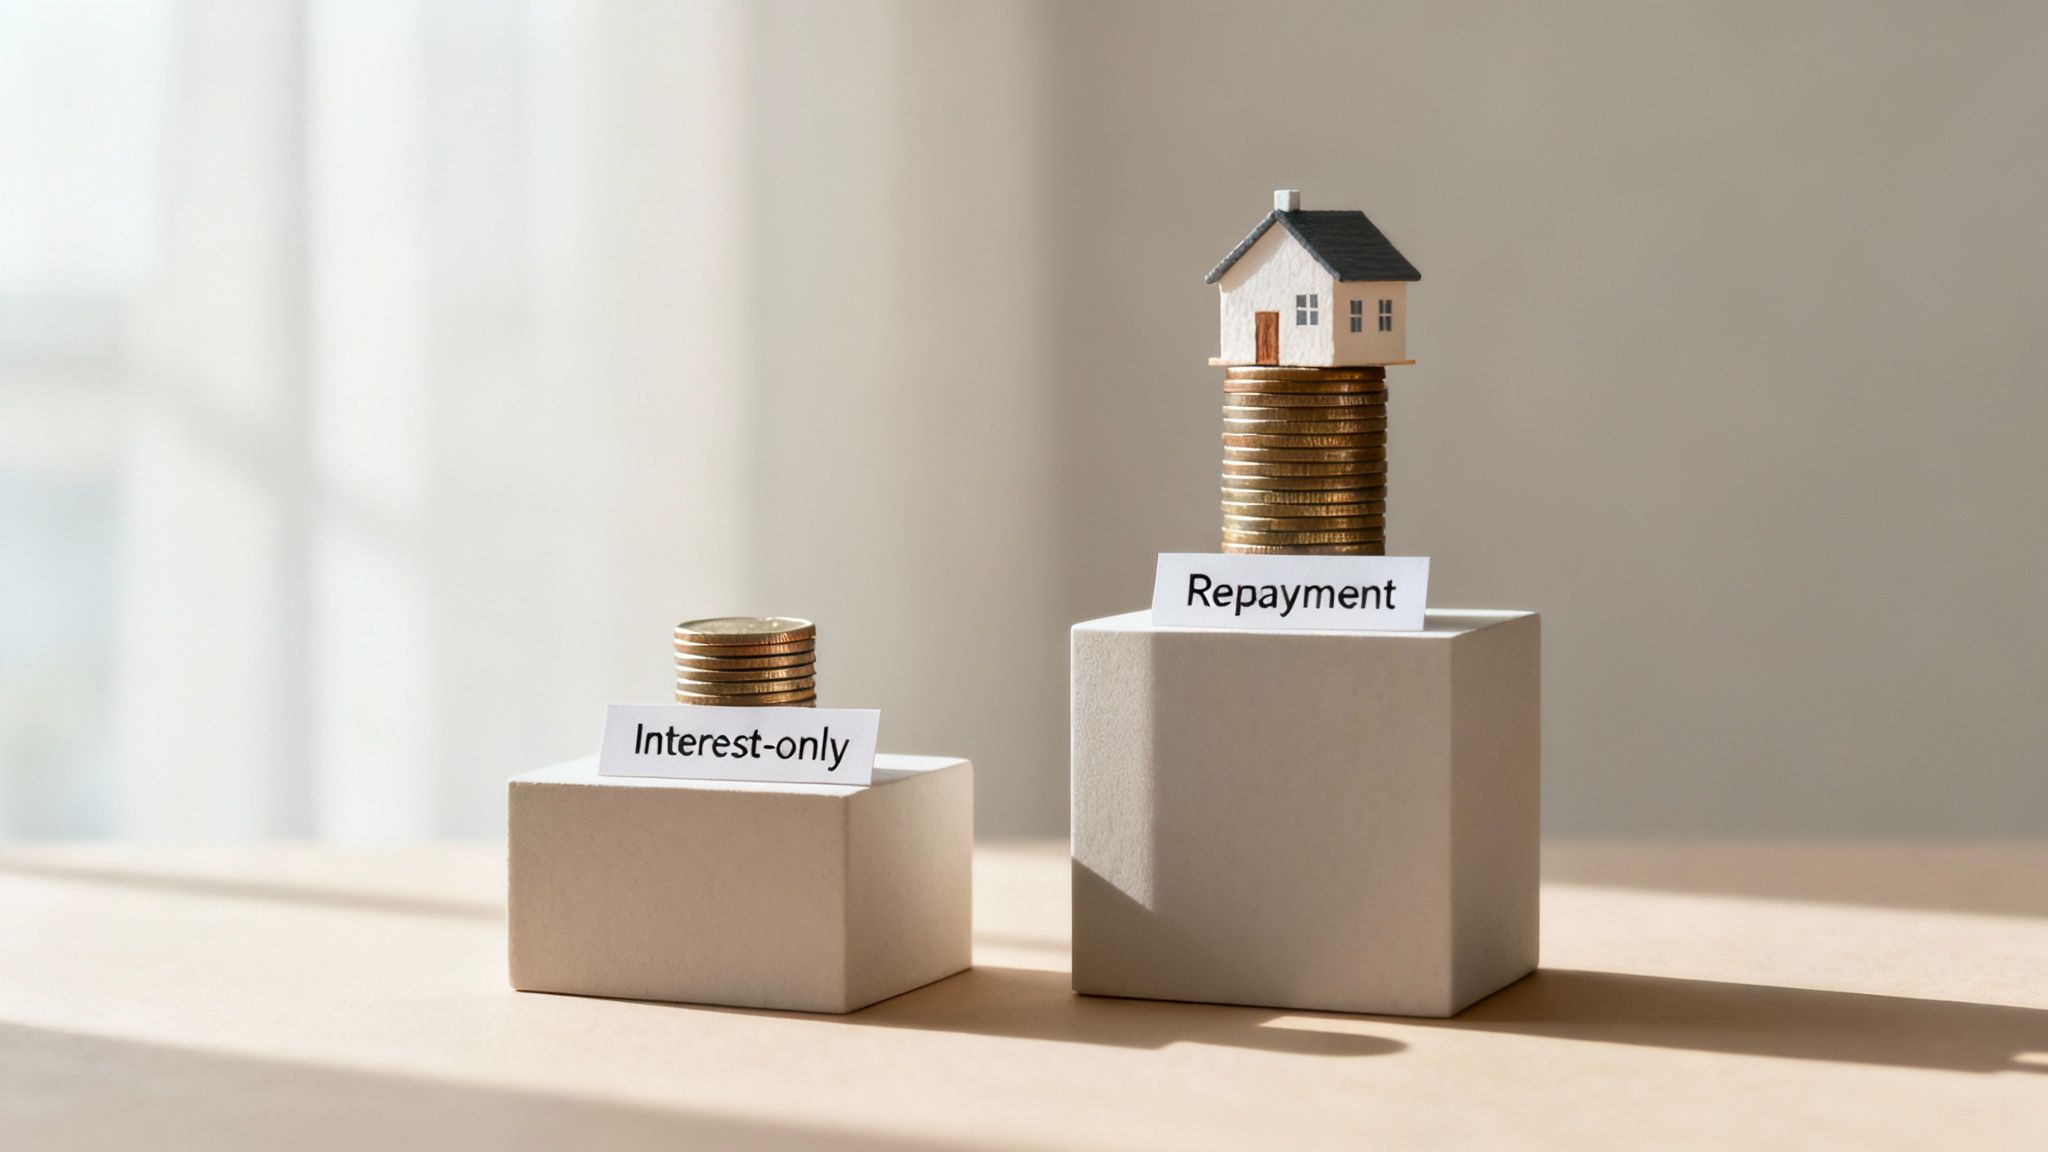
A fundamental choice for any buy-to-let investor is the type of mortgage repayment structure. Unlike a standard residential mortgage, where repayment is the norm, landlords have a strategic choice between an interest-only and a capital-repayment mortgage. This decision directly impacts your monthly cash flow, overall profitability, and the long-term financial strategy for your property portfolio.
How Each Mortgage Type Works
Understanding the mechanics of each option is the first step in making an informed decision. The right choice depends entirely on your investment goals, whether that is maximising monthly income or building a debt-free asset over time.
Interest-Only Mortgage: You pay only the interest on the loan each month. The original capital amount you borrowed remains unchanged. This results in significantly lower monthly payments and maximises cash flow. The full capital sum must be repaid in a single lump sum at the end of the mortgage term.
Repayment Mortgage: Each monthly payment consists of both an interest portion and a capital portion. This gradually reduces the loan balance over the term, guaranteeing that the property will be mortgage-free at the end if all payments are made.
Example in Action:
Consider a £200,000 buy-to-let mortgage over 25 years at a 5% interest rate.
– Interest-Only Payment: Your monthly payment would be just the interest: (£200,000 x 5%) / 12 = £833.33.
– Repayment Payment: Your monthly payment would cover interest and capital, totalling approximately £1,169.19.The interest-only option frees up an extra £335.86 in cash flow each month, but you still owe £200,000 after 25 years. The repayment option builds equity but reduces your monthly profit.
Practical Steps for Success
Choosing the right structure is a critical buy-to-let mortgage tip that requires careful planning. Your strategy should align with your financial objectives for the property and your wider portfolio.
Document Your Exit Strategy: Lenders will not approve an interest-only mortgage without a credible repayment plan. This could be the sale of the property, remortgaging, or using other investments. You must have this documented.
Model Both Scenarios: For every potential investment in areas like Chelmsford, Braintree, and Colchester, calculate the net yield and cash flow under both interest-only and repayment scenarios. This clarifies the financial trade-offs.
Consider a Hybrid Approach: You don’t need to apply a single rule to all properties. Many successful portfolio landlords use interest-only mortgages on new acquisitions to maximise cash flow for further expansion, while older, more established properties are on repayment plans to steadily reduce overall portfolio debt.
Regularly Review Your Strategy: Your financial goals and the property market can change. Review your mortgage strategy annually to ensure it continues to align with your long-term objectives, especially as property values and interest rates fluctuate.
4. Leverage Whole-of-Market Access to Find Specialist Lenders
One of the most valuable buy-to-let mortgage tips for ambitious landlords is understanding that the high street is not the entire market. Many mainstream banks have a limited appetite for anything beyond a straightforward single property investment. For landlords with complex circumstances, portfolio ambitions, or non-standard properties, specialist lenders are often the key to success, and accessing them requires a whole-of-market approach.
How Whole-of-Market Access Works
A whole-of-market mortgage broker is not tied to a small panel of lenders. Instead, they have access to a comprehensive range of mortgage products from dozens, sometimes hundreds, of lenders across the UK. This includes high street banks, building societies, and critically, specialist lenders who do not deal directly with the public. These specialist lenders often have more flexible criteria and products designed for specific landlord needs.
This access is crucial because a standard bank might decline an application based on a single factor, whereas a specialist lender may see it as an acceptable risk or even their target market. When you search for mortgage products, key details like the expected rental income, whether a licence is required on the property type, or in the local area, and the size of your existing portfolio are critical. A large portfolio, for instance, can be a reason a mainstream lender will not offer you any mortgage deals, but a specialist may welcome it.
Complex Income: Specialist lenders are more adept at underwriting applications from self-employed landlords with fluctuating profits or contractors with complex pay structures.
Adverse Credit: Applicants with minor credit issues, such as a historic late payment, may be rejected by automated high-street systems but can be approved by a specialist lender that manually assesses cases.
Portfolio Lending: Lenders vary significantly on the number of properties they will finance. A specialist portfolio lender will offer products designed for landlords with four or more properties, understanding the nuances of larger portfolios.
Property Type: Unusual properties such as HMOs (Houses in Multiple Occupation) or multi-unit freehold blocks are often only financed by specialist lenders.
Example in Action:
A self-employed landlord in Essex with three existing buy-to-let properties was rejected by three high-street banks when trying to finance a fourth. The reasons given were a combination of his portfolio size exceeding their limit and their rigid assessment of his sole trader income.By working with a whole-of-market broker like EHF Mortgages, he was introduced to a specialist portfolio lender. This lender not only accepted his self-employed accounts but also offered a portfolio mortgage product that consolidated his financing, providing a better overall rate and simplifying his admin. He secured the fourth property and a clear path to growing his portfolio to ten properties.
Practical Steps for Success
Leveraging the whole market is about finding the right key for the right lock rather than trying to force one key to fit all doors.
- Work with a Regulated Broker with Experience: Ensure you partner with a directly authorised FCA-regulated independent broker who has been in the mortgage industry for a number of years. This guarantees they have the widest possible market access and are held to high professional standards.
Be Upfront and Detailed: Provide your broker with a complete and accurate picture of your financial portfolio size and future plans from the start. This allows them to quickly filter out unsuitable lenders and pinpoint the specialists most likely to approve your case.
Discuss Your Growth Strategy: If you plan to expand your portfolio into areas such as Chelmsford, Braintree, or Colchester, tell your broker. They can align you with a lender whose products and criteria are built for scalability, avoiding future roadblocks.
Query Their Lender Panel: Ask a potential broker about their experience with specialist lenders and in what areas they have particular expertise, such as adverse credit or HMOs. This ensures their skills match your specific needs.
5. Plan for Tax Efficiency and Mortgage Interest Relief
One of the most overlooked yet impactful buy-to-let mortgage tips involves structuring your investment for maximum tax efficiency. While generating strong rental yields is crucial, how you manage your tax obligations determines your true net profit. Historically, landlords could deduct all their mortgage interest from rental income before calculating tax, but significant changes have altered this landscape for individual owners. Understanding the current rules is essential to protect your returns.
How Mortgage Interest Tax Relief Works
For individual landlords in the UK, mortgage interest is no longer fully deductible. Instead, you receive a tax credit equivalent to 20% of your annual mortgage interest payments. This change primarily affects higher- and additional-rate taxpayers who previously received relief at 40% or 45%. This shift can significantly reduce net profitability if not properly planned for.
Furthermore, the way this is calculated means your ‘on-paper’ rental income is higher, which can push some basic rate taxpayers into a higher tax bracket, a critical consideration when structuring your finances.
Tax Credit: A basic rate tax credit of 20% is applied to your mortgage interest costs.
Higher Rate Impact: Landlords paying tax at 40% or 45% will find their tax bill is substantially higher than under the old system.
Limited Company Exception: These rules do not apply to properties held within a limited company structure where mortgage interest remains a fully deductible business expense.
Example in Action:
Consider a higher-rate taxpayer landlord with a £300,000 interest-only mortgage at 5% on a property held personally.
– Annual mortgage interest: £300,000 x 5% = £15,000
– Tax relief available (as a credit): £15,000 x 20% = £3,000
– Tax payable on the £15,000 interest portion: £15,000 x 40% = £6,000
– Net Tax Cost: £6,000 (tax) – £3,000 (credit) = £3,000Under the previous system, this landlord would have saved the full £6,000 in tax. Under the current rules, their net profit is reduced by £3,000.
Practical Steps for Success
Proactive tax planning is not an option; it is a necessity for modern landlords. A poorly structured investment can result in net yields dropping significantly.
Consult a Specialist: Always work with a qualified accountant who has specific experience in property taxation. They can provide tailored advice for your personal circumstances.
Model Net Returns: When assessing a potential investment in Chelmsford, Braintree, or Colchester, always calculate your expected return based on the *net* (after-tax) yield, not the gross yield.
Consider a Limited Company: For portfolio landlords or higher-rate taxpayers holding properties within a limited company can be far more tax-efficient. You can discover more about limited company mortgages to see if this is the right strategy for you.
Keep Meticulous Records: Maintain flawless records of all rental income and allowable expenses including mortgage interest payments to ensure you claim the correct tax credit.
Stay Informed on Deductions: Tax rules can change. To further optimise your investment, keeping abreast of changes in specific deductions is crucial. For instance, you can explore the key tax deductible items for rental property in Australia to understand how different tax jurisdictions handle allowable expenses.
6. Build a Scalable Portfolio Strategy and Structure Future Growth
A crucial buy-to-let mortgage tip that separates amateur landlords from professional investors is the shift from single-property thinking to long-term portfolio strategy. Successful investors don’t just buy properties; they architect a scalable business plan designed for sustainable growth over 5, 10, or even 20 years. This involves meticulously planning how each acquisition fits into a larger picture, focusing on leveraging refinancing cycles and diversification.
How Portfolio Strategy Works
A scalable portfolio strategy is a roadmap for your property investment journey. Instead of making opportunistic purchases, you make calculated decisions that support future acquisitions. This approach considers how the LTV of your entire portfolio will be affected by a new purchase and how you can recycle equity from existing properties to fund it. Lenders that specialise in portfolio finance will assess your overall business plan, not just a single property.
This strategic thinking is vital because many lenders have limits on the number of mortgaged properties an individual can have. A well-structured plan allows you to work with the right lenders at the right time.
Sequenced Acquisitions: You plan the order of your purchases perhaps starting with high-yield properties in areas like Braintree to build cash flow before targeting capital growth in prime Chelmsford locations.
Equity Recycling: The core of the strategy involves using the capital appreciation in your properties. By refinancing every few years, you unlock tax-free equity to use as a down payment on your next purchase, creating a growth loop.
Example in Action:
An investor in Essex buys their first buy-to-let for £200,000 with a £50,000 deposit. Over three years, the property value increases to £240,000, and the mortgage is paid down slightly.
– New Property Value: £240,000
– Remortgage at 75% LTV: £240,000 x 75% = £180,000
– Outstanding Mortgage Balance (approx.): £148,000
– Equity Released: £180,000 – £148,000 = £32,000This £32,000 can now be used as a deposit for a second property, allowing the portfolio to expand without requiring new personal savings. Repeating this process is a cornerstone of portfolio building.
Practical Steps for Success
Building a robust portfolio requires foresight and financial discipline. It’s about creating a system that fuels its own expansion.
Create a 5-10 Year Plan: Define your goals. Do you want to acquire two properties a year? What target income or portfolio value are you aiming for? Your plan should outline target property types, locations, and financing milestones.
Plan Your Refinancing Cycles: Diarise your fixed-rate mortgage terms. Plan to review and potentially remortgage every two to three years to assess equity and secure competitive rates.
Diversify Your Assets: Don’t put all your eggs in one basket. A resilient portfolio might include a mix of standard buy-to-lets in Colchester, a high-yield HMO in Chelmsford, and perhaps a commercial unit to spread risk across different tenant types and markets.
Maintain Strong Cash Reserves: Always keep a buffer of at least 3-6 months’ operating costs (including mortgage payments) for your entire portfolio. This protects you from void maintenance issues and economic downturns.
Partner with a Portfolio Broker: A specialist broker understands the nuances of portfolio lending and has relationships with lenders who cater to professional landlords. They can help you structure deals and manage your overall LTV effectively.
7. Maintain Financial Reserves and Plan for Contingencies
One of the most overlooked but vital buy-to-let mortgage tips is building a robust financial safety net. A successful property investment isn’t just about generating monthly income; it’s about having the resilience to withstand unexpected costs and periods without rent. Underestimating the need for contingency funds is a primary reason why property portfolios fail. Lenders are increasingly scrutinising an applicant’s cash reserves, viewing them as a key indicator of a landlord’s viability and preparedness.
How Contingency Planning Works
Financial reserves act as a buffer insulating your investment from the inevitable challenges of being a landlord. These funds are set aside specifically to cover costs when rental income stops or a large unplanned expense arises. This could be anything from a boiler breakdown and emergency roof repairs to a tenant defaulting on rent leading to a lengthy void period. Without adequate reserves a single unforeseen event could force you to use personal savings take on high-interest debt or even sell the property at a loss.
Your reserve fund should be a liquid cash account easily accessible but separate from your daily finances to avoid temptation. The goal is to have enough capital to cover all property-related outgoings for a set period ensuring you can meet your mortgage obligations no matter what.
Standard Reserve Goal: Aim to hold 3-6 months of the property’s total operating costs in a separate account.
Maintenance Allocation: A common rule is to budget 1% of the property’s value for annual maintenance. For older properties in areas like Braintree or period homes in Colchester, this could be higher around 2-3%.
Example in Action:
A landlord owns a four-property portfolio with a total mortgage debt of £800,000.
– Monthly mortgage payments (interest-only at 4.5%): £3,000
– Monthly insurance management fees and other costs: £1,000
– Total Monthly Operating Costs: £4,000
– Six-month reserve fund required: £4,000 x 6 = £24,000This landlord needs to maintain at least £24,000 in a dedicated accessible account to protect their portfolio from financial shocks such as a prolonged void period affecting one or two properties simultaneously.
Practical Steps for Success
Building and maintaining this fund requires discipline and strategic planning. Integrating it into your investment strategy from day one is crucial for long-term success.
Calculate All Costs: Tally up every expense associated with your property, including mortgage payments, insurance, letting agent fees, service charges, and an estimate for annual repairs and certifications.
Factor in Voids: When calculating your reserve target, assume a void period of 5-8% of the annual rent. This accounts for the time between tenancies when no income is being generated.
Keep Funds Separate: Open a dedicated high-interest savings account for your reserves. Using a different bank from your main current account adds a layer of discipline, making it less likely you will dip into the funds for non-emergencies.
Stress Test Your Finances: Just as lenders do, you should stress-test your portfolio. Recalculate your mortgage payments using a higher interest rate (e.g. 6%) to understand how a rate rise would impact your outgoings and adjust your reserve target accordingly.
Review and Replenish: Review your reserve fund annually or whenever you add a new property. If you use funds for a repair, create a plan to replenish them as quickly as possible. Crucially, avoid using these reserves to fund deposits for portfolio expansion; use refinancing strategies instead.
Buy-to-Let Mortgage Tips — 7-Point Comparison
Item | 🔄 Implementation Complexity | 📊 Expected Outcomes | 💡 Ideal Use Cases | ⭐ Key Advantages |
|---|---|---|---|---|
Understand Rental Income Requirements and Stress Testing | Medium – requires lender-specific calculations and realistic rent valuations | Clear borrowing limits; prevents over-borrowing but may reduce capacity | Pre-application affordability checks; landlords assessing purchase feasibility | Risk mitigation; sustainable borrowing; lender confidence |
Secure the Right Loan-to-Value Ratio for Better Terms | Medium – deposit planning and portfolio LTV modelling | Lower rates, stronger approval odds, faster equity build | Investors with available capital or refinancing plans to reduce LTV | Lower interest rates; improved refinancing options; reduced lender risk |
Choose Between Interest-Only and Repayment Mortgages Strategically | Medium – scenario modelling and documented exit strategy for interest-only | IO: improved monthly cash flow; Repayment: gradual equity build and reduced debt | Cash-flow focused investors (IO) vs long-term debt reduction (repayment) | IO: maximised cash flow; Repayment: predictable equity accumulation |
Leverage Whole-of-Market Access to Find Specialist Lenders | Low–Medium – broker-driven process, requires detailed disclosure | Higher approval probability for complex cases; better tailored terms | Self-employed, adverse credit, multi-property portfolios, unusual properties | Broader lender choice; specialist solutions; stronger negotiating power |
Plan for Tax Efficiency and Mortgage Interest Relief | High – tax rules vary and need professional interpretation | Significant net yield improvement (material to returns; often 20–30% effect) | Larger portfolios, higher tax brackets, investors considering company ownership | Substantial after-tax cash flow improvement; optimised long-term wealth building |
Partner with EHF Mortgages to Secure Your Financial Future
The journey into property investment is both exciting and complex. As we have explored throughout this guide, securing the right buy-to-let mortgage is not merely a transactional step; it is the strategic foundation for a successful, profitable property portfolio. From understanding the nuances of rental income stress tests and Interest Coverage Ratios (ICRs) to strategically choosing between interest-only and repayment structures, every decision has a significant long-term impact on your financial future.
We have delved into the critical importance of achieving the right loan-to-value (LTV) ratio to unlock better interest rates and more favourable terms. We have also highlighted the need to look beyond high-street lenders and to leverage whole-of-market access to find specialist products tailored to unique circumstances, whether you are a portfolio landlord in Chelmsford or a first-time investor in Braintree. Furthermore, a forward-thinking approach to tax efficiency and the careful consideration of a limited company structure can profoundly affect your net returns, making it one of the most vital buy-to-let mortgage tips for serious investors.
Key Takeaways for Your Investment Journey
Mastering these concepts transforms you from a passive landlord into a strategic property investor. Here are the core principles to carry forward:
Strategy Over Rate-Chasing: A low headline rate is appealing but is useless if the lender’s stringent stress tests or portfolio limits prevent you from securing the finance. A successful mortgage strategy considers rental yield, tax structure, and future portfolio growth in unison.
Proactive Financial Planning: The best time to prepare for a mortgage application is months before you need it. Maintaining clean credit files, organising your financial documentation, and building a contingency fund are non-negotiable steps that demonstrate your credibility as a borrower.
Specialist Advice is an Investment, Not a Cost: The buy-to-let market is a labyrinth of changing regulations, niche lender criteria, and complex tax rules. Attempting to navigate it alone can lead to costly mistakes, rejected applications, or a mortgage product that hinders rather than helps your growth. An expert broker provides the map and the compass.
Ultimately, the goal is not just to acquire a property but to build a sustainable, scalable, and profitable asset base. Whether your ambition is to create a supplementary income stream for retirement or to build a full-scale property empire across Essex, the principles remain the same. A meticulously planned financial structure supported by expert advice is the bedrock of your success. By internalising these buy-to-let mortgage tips, you are equipping yourself with the knowledge to make informed strategic decisions that will pay dividends for years to come. Your property portfolio is a business, and every successful business starts with a solid financial plan.
Ready to turn these tips into action?
Navigating the complexities of rental calculations, lender criteria, and portfolio structuring requires specialist expertise.
The team at EHF Mortgages has over 35 years of experience providing tailored advice and whole-of-market access to investors across Chelmsford, Braintree, and Colchester. Let us build a bespoke mortgage strategy that aligns with your investment goals. Visit our Contact Us page to arrange your no-obligation consultation today.





